EPF’s i-Emas monthly payouts could help retirees avoid burning through savings公积金局 (EPF) 的 i-Emas 月度分红可以帮助退休人员避免耗尽积蓄。
MELAKA, Oct 19 — Monthly retirement savings withdrawals under the Employees Provident Fund’s (EPF) i-Emas retirement savings scheme could help retirees manage their finances...
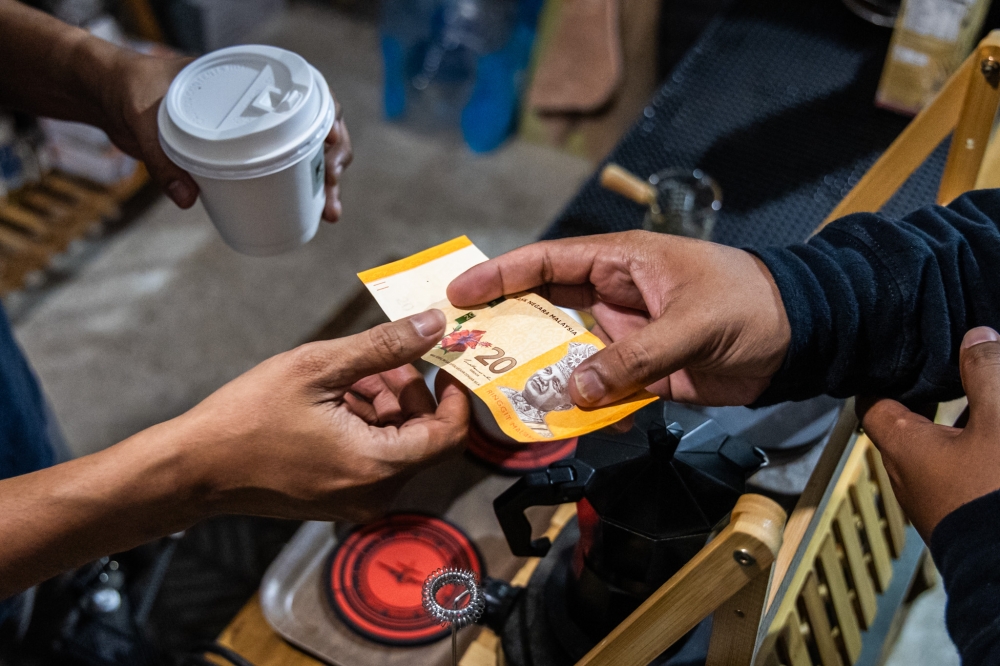
The i-Emas retirement savings scheme, introduced under Budget 2027, allows eligible Employees Provident Fund (EPF) members to receive monthly withdrawals instead of taking a lump sum upon retirement.
This initiative is designed to provide retirees with a regular income stream, mitigating the risk of rapidly depleting their savings and enabling remaining funds to continue earning annual dividends.
Proponents suggest it aids in systematic financial management post-retirement and supports long-term financial planning.
MELAKA, Oct 19 — Monthly retirement savings withdrawals under the Employees Provident Fund’s (EPF) i-Emas retirement savings scheme could help retirees manage their finances more systematically while reducing the risk of exhausting their savings within a short period.
Private sector employee Kalpita Jatin Doshi, 30, said the approach was appropriate as it provided retirees with a regular income stream, particularly those who faced difficulties securing employment or a steady source of income after the age of 55.
The reservation executive said staggered withdrawals would enable retirees to control their daily spending while allowing the remaining savings in their EPF accounts to continue earning annual dividends.
“The i-Emas initiative is very good as it provides a continuous monthly income, with a minimum withdrawal of RM100.
“If EPF savings are withdrawn in a lump sum, there is a risk of the money running out quickly. Monthly withdrawals not only help manage spending but also allow the remaining savings in EPF accounts to continue earning annual dividends,” she told Bernama.
Sales executive Muhammad Uzaibah Fathiha Mohd Taib, 28, said the facility also allowed EPF members to plan their long-term finances in a disciplined manner, particularly to meet their needs after retirement.
He said early planning was important to ensure that savings accumulated throughout their working lives could sustain them during retirement, which could last for many years.
“As young people, having a long career ahead of us allows us to accumulate as much savings as possible.
“Having a scheme like this allows us to plan our long-term finances better for retirement, family needs, housing and activities in our later years,” he said.
The i-Emas scheme was announced under Budget 2027, which allows eligible members to receive monthly payments from their Age 55 and Age 60 Withdrawals instead of withdrawing their entire savings in a lump sum, while the remaining balance in their EPF accounts continues to earn annual dividends.
The approach aims to help members manage their post-retirement cash flow more systematically and extend the period over which their savings can be used to meet daily needs. — Bernama
Luxury giants face shrinking sales in China as second‑hand market rockets towards 100 billion yuan
Japan’s yuzu makers see fresh opportunity in Malaysia’s halal sector
US-India trade deal was down to the ‘last 1pc’. Why is it still stuck?
Lawmakers to address M40 aid, Madani allocations and Tourism Compliance Focus Zone effectiveness in Dewan Rakyat today
PM Anwar: Malaysia prepared to assist Indonesia in tackling forest fires
Hazy Monday dawns, 26 stations across Kuala Lumpur, Johor, Sarawak record poor air
根据 2027 年财政预算案推出的 i-Emas 退休储蓄计划,允许符合条件的雇员公积金 (EPF) 会员每月领取提款,而不是在退休时一次性领取。
这项计划旨在为退休人员提供稳定的收入来源,降低其储蓄迅速耗尽的风险,并使剩余资金能够继续获得年度分红。
支持者认为,它有助于退休后进行系统性的财务管理,并支持长期财务规划。
马六甲,10 月 19 日讯——根据雇员公积金局 (EPF) 的 i-Emas 退休储蓄计划,每月提取退休储蓄可以帮助退休人员更系统地管理财务,同时降低在短期内耗尽储蓄的风险。
30岁的私营部门员工卡尔皮塔·贾廷·多希表示,这种做法是合适的,因为它为退休人员提供了稳定的收入来源,特别是那些在55岁以后难以找到工作或获得稳定收入来源的人。
预订主管表示,分阶段提取资金可以让退休人员控制日常开支,同时让他们的公积金账户中的剩余储蓄继续赚取年度股息。
“i-Emas计划非常好,因为它能提供持续的月收入,最低提款额为100令吉。
她告诉马新社:“如果一次性提取公积金储蓄,资金可能会很快用完。每月提取不仅有助于控制支出,还能让公积金账户中的剩余储蓄继续获得年度分红。”
28岁的销售主管穆罕默德·乌扎伊巴·法蒂哈·莫哈末·泰布表示,该设施还允许公积金会员以有纪律的方式规划他们的长期财务,特别是满足他们退休后的需求。
他表示,提前规划非常重要,这样才能确保他们在工作生涯中积累的积蓄能够维持他们退休后的生活,而退休生活可能会持续很多年。
“作为年轻人,我们还有很长的职业生涯,这使我们能够尽可能多地积累积蓄。”
他说:“有了这样的计划,我们就能更好地规划退休、家庭需求、住房和晚年活动等方面的长期财务。”
i-Emas 计划是在 2027 年财政预算案中宣布的,该计划允许符合条件的成员从其 55 岁和 60 岁提款中按月领取款项,而不是一次性提取全部储蓄,而其 EPF 账户中的剩余余额将继续获得年度股息。
该计划旨在帮助成员更系统地管理退休后的现金流,并延长储蓄用于满足日常需求的期限。——马新社
随着二手市场规模逼近1000亿元人民币,奢侈品巨头在中国的销售额正面临下滑。
日本柚子生产商看到了马来西亚清真产业的新机遇
美印贸易协议只差最后1%就能达成,为什么至今仍未敲定?
议员们今天将在下议院讨论M40援助、马达尼拨款和旅游合规重点区域的有效性问题
安华总理:马来西亚准备协助印尼应对森林火灾
周一清晨雾霾弥漫,吉隆坡、柔佛和砂拉越共26个气象站空气质量记录不佳