The Pentagon wants industry to transform again to meet demand. Can it?五角大楼希望工业界再次转型以满足需求。它能做到吗?
In 30 years, the Pentagon went from a defense industry it considered too large to sustain, to one now too small to surge.
WASHINGTON — About two dozen leaders from the defense industry joined the secretary of defense for dinner in fall 1993. After the meal, later known as “the Last Supper,” came a half-hour briefing.
The topic was consolidation. The Cold War was over, which meant America would spend less on defense. That also meant less money for the companies in the room. Officials flashed a black-and-white graph onto the wall, showing a plunge in how many contractors the Pentagon could afford. Companies would likely need to merge if they wanted to survive.
Norm Augustine — then-chief executive of Martin Marietta, which itself merged in 1995 to become Lockheed Martin — had been there, sitting beside the defense secretary. A day later, he returned to the Pentagon and grabbed a copy of that chart, expecting it to be a historic document. He still has it today.
Within a decade, the number of large prime contractors plummeted from 51 to five, creating the modern defense industry. Lockheed merged with Martin. Boeing merged with McDonnell Douglas.
“Sitting there at the Last Supper, I felt like I was sitting in a historical pivot point,” Augustine told Defense News. “They did the best [with] a bad hand, and we’re now paying the price for the bad hand.”
An F-117 Nighthawk stealth attack aircraft undergoes assembly at a Lockheed Martin facility around 1980. (Lockheed Martin)
That price is a defense sector that can’t move as quickly as the Pentagon wants it to. America is now supplying materiel for the wars in Ukraine and Israel , which started a year and a half apart. The high demand has strained an industry that often struggled to meet needs long before Russia’s full-scale invasion of Ukraine in February 2022.
And these wars aren’t even the Defense Department’s top priority; that’s China, whose massive military buildup over the last 20 years is the pace America’s leaders say they must match. Nowhere is this clearer than in the Pentagon’s new defense-industrial strategy, which says China’s industrial might in many areas “vastly exceeds” that of the U.S. and its allies.
In response, the plan calls for “generational” investment in the industrial base. To do so, the Pentagon is now showing a new set of graphs.
Bill LaPlante, the department’s top weapons buyer, has a wall in his office covered with images plotting how long it would take to build more missiles and other munitions. His deputies are sharing these with company after company, he said — though the Pentagon isn’t making them public.
Call it a tale of two charts: In 30 years, the Pentagon went from a defense industry it considered too large to sustain, to one now too small to surge. To understand that path, Defense News spoke with analysts and industry executives as well as top industrial base policy officials dating back to the Clinton administration. They likened the sector to something of a spring-loaded door — where capacity slammed shut due to smaller budgets, changing preferences and a thinning workforce.
That door is now creaking open again as America retools its defense industry, workforce and suppliers to compete with an advanced adversary.
“It’s dusting off a lot of skills that we’ve had in this country that we haven’t used in a while,” LaPlante told reporters in December at the Reagan National Defense Forum.
Experts on America’s defense industry tend to speak about it like an intro economics course. They often note the sector doesn’t move like other markets.
Defense companies build what governments want, but rarely any more or anything different. The Pentagon’s orders, hence, have an unusual amount of sway over the shape of the companies fulfilling them.
“The defense industry is hypersensitive to and responsive to its customers,” said Steve Grundman, a senior fellow at the Atlantic Council think tank.
Grundman worked in the Pentagon in the 1990s, in the wake of the peace dividend. Military spending had surged under the Reagan administration as the U.S. competed with the Soviet Union. But when the USSR dissolved in 1991, ending the Cold War, America had no opponents left to outcompete. Defense spending fell each fiscal year from 1985 to 1998, according to the Center for Strategic and Budgetary Assessments think tank.
Specifically, the Pentagon’s spending on procurement, research, development and construction dropped 44% during that time period, CSBA found.
America needed a defense industry built for peacetime. So arrived the Last Supper, a name Augustine himself gave the 1993 dinner. Even at the time, he said, it appeared to be sound policy. Defense spending was bound to fall, leaving the Pentagon with two choices: a sprawling industry versus a smaller, more efficient one.
Defense officials encouraged the latter. Alongside the plummet of prime contractors, the number of mid-tier and small suppliers also cratered as companies merged in order to lower costs.
Eventually the government said enough was enough. In the late 1990s, it blocked Lockheed Martin’s plan to buy Northrop Grumman. The era of major consolidation was over.
Its effects were twofold: less competition and less ability to surge. The first, in many cases, has meant the Pentagon’s orders take longer, cost more and are vulnerable to brittle supply chains . The second — caused both by consolidation and more efficient manufacturing techniques — makes it harder to respond to sudden conflicts.
Heading into the 2000s, leaders in large part began to favor weapons that were more advanced but would be fewer in number. Defense Secretary Donald Rumsfeld labeled it a “transformation” that would vault the Pentagon’s arsenal a whole generation ahead.
Some of these advanced weapons — such as the Army’s Future Combat System and the Navy’s Littoral Combat Ship — did not work out as intended. And the shift toward fewer, more capable systems further encouraged companies to consolidate.
In 1998, five companies built surface ships and two made tracked combat vehicles. By 2020, those numbers had fallen to two and one respectively.
The Pentagon reported the number of U.S. contractors building tracked combat vehicles fell from three in 1990 to one in 2020. An employee of that firm, General Dynamics, guides an M1A2 tank off a train on Jan. 5, 2023. (Staff Sgt. Rakeem Carter/U.S. Army)
“As dumb as it sounds, given how much we spend on defense, oftentimes the volume for any single supplier isn’t enough,” said Dave Bassett, a retired Army lieutenant general, who until December ran the Defense Contract Management Agency.
The peace dividend did not survive America’s wars in Iraq and Afghanistan.
The 9/11 attacks followed by the two conflicts swelled the Defense Department’s budget. When adjusted for inflation and including supplemental funding, Pentagon spending rose an average of 7% from fiscal 1999 to fiscal 2008, according to CSBA.
This spending went toward a new set of threats.
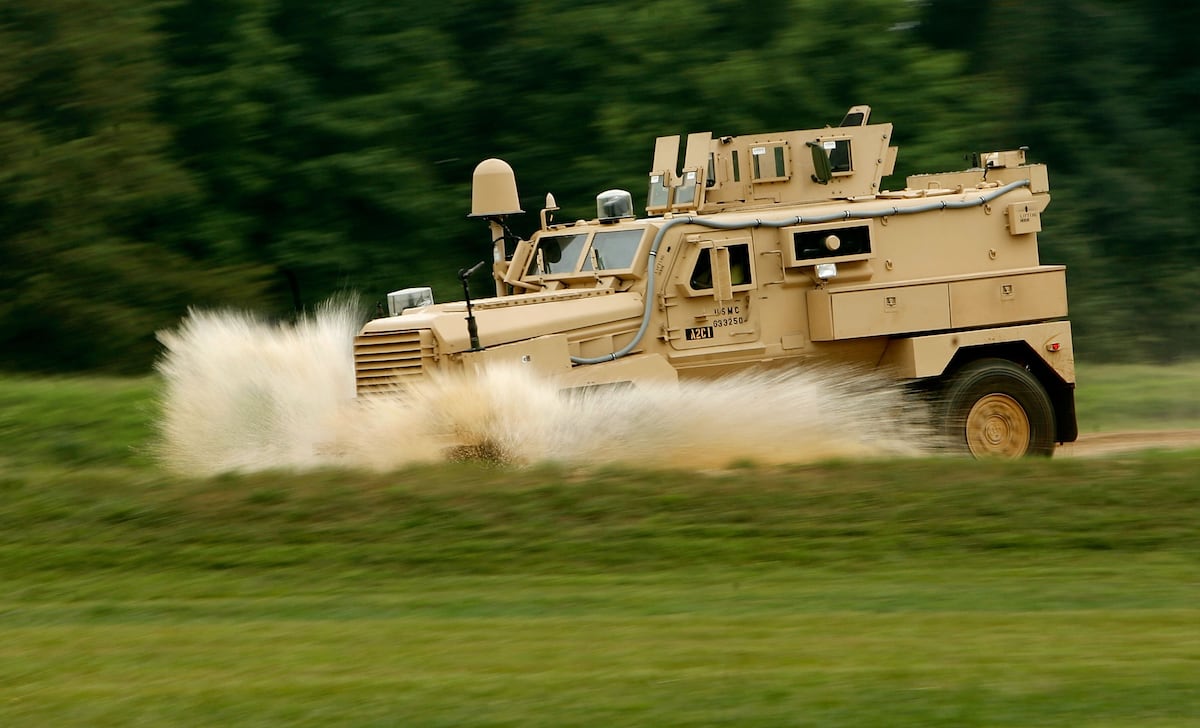
As an example, Bassett and other experts interviewed by Defense News singled out a class of heavily armored vehicles developed for the wars. The mine-resistant, ambush-protected vehicle program was Defense Secretary Bob Gates’ top priority. With heavy investment, the Pentagon fielded more than 13,000 MRAP vehicles in three years.
The program has since become a talisman for some who argue the defense industry can move nimbly if given the proper resources. But it’s also a reminder of where those resources went for more than 15 years. From 2001 onward, the Pentagon needed weapons for counterinsurgencies.
Those are far from what Ukraine needs to defend itself against Russia — an industrial-age war defined by the use of artillery and small drones. Even further are the needs of defending Taiwan, an island nation threatened by a leading manufacturing powerhouse.
“If what you’re facing is an Iraqi threat, you’re probably not going to have the same capacity as when you face a Russian and the Chinese threat,” said Bill Lynn, deputy defense secretary during the Obama administration and now chief executive of Leonardo DRS.
And the change in capacity had become clear to defense officials.
Brett Lambert, who ran industrial base policy for the Pentagon while Lynn was deputy secretary, remembers a tornado in 2011 that struck Joplin, Missouri — nearly hitting a major battery supplier.
A deadly tornado damaged Joplin, Mo., in May 2011. (Brendan Smialowski/AFP via Getty Images)
“We realized that even though the plant itself was not hit, we didn’t have a backup,” Lambert said. “That was a wake-up call to me.”
Another warning came in the form of a four-year study of major weapons programs Lambert helped lead. He found, in large part, that prime contractors didn’t understand their own supply chains.
But while the alarm went off, no one woke up, said Robert Lusardi, a former Pentagon industry official. The study’s data, he noted, largely faded into the ether.
“Nobody used it,” he said.
‘There’s never just one problem’
Eric Chewning was vacationing with his family at the Outer Banks in summer 2017.
Sitting on the North Carolina beach with his kids, Chewning — then a partner at the consulting firm McKinsey and Co. — scrolled through his phone and saw a news release about an executive order. President Donald Trump was instructing the Pentagon’s first top-down review of its defense-industrial base since the Eisenhower administration.
“I say to myself: ‘Who are they going to get to do that?’ ” Chewning told Defense News in an interview.
Later that day, he was walking back from the beach when he got a call from the Pentagon asking if he would interview for the top industrial base policy role. In October, he took the job, which meant he would be the one running the study.
“The mindset was: How do we holistically now transition ourselves from the post-9/11 wars, where there really wasn’t ever a question around our ability to generate enough material capability, to one focused on competition with an economic peer?” Chewning said.
What he found is that doing so wouldn’t be easy — in large part because of what was happening with the American workforce. By the time the defense industry consolidated in the 1990s, the U.S. was decades into a deep manufacturing slide.
From the late 1970s to 2017, the country lost 7.1 million manufacturing jobs, or 36% of the sector’s workforce, according to the study Chewning led . Such declines serve as a challenge to any attempt to quickly bulk up America’s defense industry. Even with more advanced factories that now heavily rely on robotics, weapons still need people who know how to build them.
This is part of why capacity is so difficult to add once it’s gone, said Bassett, the retired Army general. It takes years to find and train skilled workers, as companies across the country have seen in the recently tight labor market.
While leading the Defense Contract Management Agency, Bassett studied business traits that would help predict manufacturing problems. A significant one he found was the share of blue-collar employees who had been on the job for less than a year; once it reached a certain threshold, he said, quality issues were almost guaranteed.
While the 2018 study led to some reforms, it did not reverse the trend in manufacturing, which only got worse as older workers retired en masse during the COVID-19 pandemic . Like many reports in Washington, it pointed to major issues that existed alongside other difficulties, all competing for time and money.
A worker leaves the Boeing plant where 737 Max airplanes are assembled on April 21, 2020, shortly after it reopened, in Renton, Wash., following the outbreak of COVID-19. (Stephen Brashear/Getty Images)
“There’s never just one problem,” said Chewning, now a vice president at the shipbuilder HII. “The immediate problems get the most attention.”
By 2022, the problem had become immediate. Russia launched a full-scale invasion of Ukraine, and Washington continued sending weapons to aid Kyiv.
The U.S. has given Ukraine a staggering amount of security aid — more than $44 billion since February 2022 . Despite that sum, one of the lessons for many in the Pentagon has been that industry was unprepared for a crisis.
Arguably, nowhere is this more obvious than in America’s supply of 155mm artillery shells.
The 155mm round — next to small drones – has defined fighting in Ukraine. For self-defense, Kyiv needs 60,000-80,000 shells per month, Michael Kofman, an analyst at the Carnegie Endowment for International Peace, told Defense News.
That rate well surpasses the pace at which Ukraine’s Western allies could resupply them. Even with an extra $1.5 billion from Congress in 2023 to increase production, America was making 28,000-30,000 shells in December, said LaPlante, who is in charge of acquisition and sustainment at the Pentagon.
The Defense Department’s goal is to reach 100,000 rounds per month by the middle of 2025. But that pace likely won’t be possible without more funding from Congress, which has stalled a security spending bill requested by the White House.
But funding hasn’t slowed down production in recent years; from FY16 to FY23, Congress added 7.3%, or $79.3 billion, to the White House’s requested Pentagon procurement fund, according to CSBA. The problem is inconsistent demand, which LaPlante illustrated with another chart last fall.
Starting with the Gulf War 30 years ago, munition orders have gone up and down in a series of peaks and valleys: A crisis breaks out, the Pentagon surges supply, it reaches the number a couple years later, then the crisis wanes and supply falls.
“That’s one of the challenges that we have now — that inability to make adjustments because of the lack of investment that we’ve made to the industrial base historically,” Justin McFarlin, who leads industrial base development for the Pentagon, told Defense News.
Munitions are often at high risk for such whiplash. Eric Fanning noticed this pattern after years of holding senior positions with the Navy, the Air Force and the Army. Much of each service’s spending power was sewed up in large systems, such as aircraft carriers and fighter jets. More inexpensive items ended up tapered to make the budget fit. And because the Pentagon’s demand affects supply, the companies fulfilling those orders trimmed capacity over time.
Several 155mm artillery projectiles are stored during a manufacturing process at the Scranton Army Ammunition Plant in Pennsylvania on April 13, 2023. (Matt Rourke/AP)
Now orders are up again — this time for 155mm shells and a bevy of other munitions. For some, Congress has allowed the Pentagon to issue long-term contracts that keep demand stable for years. But for others, companies are left worrying government demand won’t last, according to Fanning, now head of the Aerospace Industries Association.
“That sense of long-term commitment is still not quite there,” he said.
‘First contact with the enemy’
The Pentagon says it’s signaling future commitments in its new industrial base strategy . The document focuses on four areas: creating resilient supply chains, ensuring workforce readiness, creating business-friendly acquisition policies and bolstering the national security marketplace.
“These are not new ideas,” Halimah Najieb-Locke, acting deputy for industrial base policy, told Defense News. “But they haven’t been said with the [needed] authority.”
In a separate briefing with reporters in January, Najieb-Locke previewed the Pentagon’s goals for its defense-industrial base over the next three to five years. One is to speed up long-lead items, such as ball bearings or solid-rocket motors that slow down the production of important weapons. Others include retooling obsolete parts of the supply chain and using more funding from the Defense Production Act, which allows the Pentagon to issue national security-related grants .
“We no longer can afford to ignore [issues in the industrial base] and hope for better,” Najieb-Locke told Defense News. “We have to take decisive action.”
But there are problems outside of the Pentagon’s control.
The first is politics. As of publication, Congress had yet to pass a full defense spending bill — the latest entry in more than a decade of continuing resolutions . Defense remains a largely bipartisan issue, but there is a widening gap within the Republican Party — one reason Congress hasn’t passed additional aid for Ukraine, Israel and Taiwan.
Today’s security environment “demands a substantial, long-term increase in resources for our national defense,” Sen. Roger Wicker, R-Miss., the ranking member of the Senate Armed Services Committee, told Defense News in a statement.
Sen. Roger Wicker, r-Miss., speaks as Senate Republicans hold a news conference on Jan. 11, 2024. (Andrew Caballero-Reynolds/AFP via Getty Images)
Some of his colleagues in the House are more skeptical. “The American people work diligently to earn every dollar, but it seems the [Defense Department] has become a master of squandering those funds without batting an eye,” Rep. Glenn Grothman, R-Wis., told Defense News in December .
The second external problem is innovation. In decades past, the Pentagon used to be upstream of new technology — think GPS or the internet. It’s since found itself downstream, said Lynn, the former deputy defense secretary, and much of the current advances in artificial intelligence and drones are coming from the commercial sector.
Learning how to better work with these companies is one of the strategy’s goals. Doing so, said Najieb-Locke, will involve updating the Pentagon’s buying policies to better align with the commercial sector — a market that the Pentagon has less influence over.
“Because of that rapid change [in technology], a lot of our assumptions of what will be there in time of need have [proved] to be in some cases overblown,” said Najieb-Locke.
A third challenge is America’s adversaries. The Russia-Ukraine and Israel-Hamas wars are a reminder that competitors ultimately help decide how fast America’s defense industry must work, and when.
Chris Michienzi learned this lesson from her time working on the Pentagon’s industrial base policy. For about eight years she helped steer the department’s approach to industry and saw challenges evolve. When the war in Ukraine began in 2022, she was one of a few officials working on aid to Kyiv.
Many of the problems of the last 30 years were on display. A worker shortage hampered attempts to surge key munitions, she cited as an example.
“The department gets the industrial base that it pays for,” she said.
Michienzi left her post last summer. In January, when Defense News spoke with McFarlin, who leads industrial base development for the Pentagon, the interview took place in Michienzi’s old office — a small, windowless cube.
No one had filled the space, and it was instead turned into a conference room — helpful for McFarlin as he briefed companies on the government’s new strategy.
“The saying I grew up [with] was: No plan survives first contact with the enemy,” McFarlin said. “We can plan, but we also have to be able to pivot and adjust.”
Noah Robertson is the Pentagon reporter at Defense News. He previously covered national security for the Christian Science Monitor. He holds a bachelor’s degree in English and government from the College of William & Mary in his hometown of Williamsburg, Virginia.
华盛顿——1993 年秋季,大约二十几位国防工业界的领导人与国防部长共进晚餐。晚餐后,进行了半小时的简报会,这顿晚餐后来被称为“最后的晚餐”。
会议的主题是整合。冷战结束,这意味着美国将减少国防开支。这也意味着在场各公司的收入会减少。官员们在墙上展示了一张黑白图表,显示五角大楼能够负担的承包商数量大幅下降。如果这些公司想要生存下去,很可能需要合并。
诺姆·奥古斯丁——时任马丁·玛丽埃塔公司首席执行官,该公司于1995年并入洛克希德·马丁公司——当时也在场,就坐在国防部长旁边。一天后,他重返五角大楼,拿了一份那张图表的副本,以为它会成为一份历史性文件。他至今仍保存着这份图表。
十年之内,大型主承包商的数量从51家骤减至5家,现代国防工业由此诞生。洛克希德公司与马丁公司合并,波音公司与麦克唐纳·道格拉斯公司合并。
“坐在最后的晚餐旁,我感觉自己正处于一个历史的转折点,”奥古斯丁告诉《防务新闻》。“他们用糟糕的牌局做到了最好,而我们现在正在为糟糕的牌局付出代价。”
大约在1980年,一架F-117“夜鹰”隐形攻击机在洛克希德·马丁公司的工厂进行组装。(洛克希德·马丁公司)
这种价格使得国防工业无法像五角大楼希望的那样快速运转。美国目前正在为乌克兰和以色列的战争提供物资,这两场战争相隔一年半爆发。高需求已经使该行业不堪重负,而早在2022年2月俄罗斯全面入侵乌克兰之前,该行业就常常难以满足需求。
而这些战争甚至都不是国防部的首要任务;首要任务是应对中国。过去20年里,中国军力的大规模扩张,正是美国领导人所说的他们必须追赶的速度。五角大楼新的国防工业战略对此体现得尤为明显,该战略指出,中国在许多领域的工业实力“远远超过”美国及其盟友。
作为回应,该计划呼吁对工业基础进行“代际”投资。为此,五角大楼现在展示了一组新的图表。
国防部首席武器采购官比尔·拉普兰特办公室的一面墙上贴满了图表,上面绘制着制造更多导弹和其他弹药所需的时间。他说,他的副手们正在与各家公司分享这些图表——尽管五角大楼并未公开这些图表。
不妨称之为“两张图表的故事”:30年间,五角大楼的国防工业规模从最初被认为过于庞大而难以维持,如今却又小到无法快速扩张。为了理解这一转变历程,《防务新闻》采访了分析师、行业高管以及克林顿政府时期的高级工业基础政策官员。他们将国防工业比作一扇弹簧门——由于预算缩减、需求变化和劳动力短缺,产能迅速关闭。
随着美国对其国防工业、劳动力和供应商进行调整,以与先进的对手竞争,这扇门现在又吱呀一声打开了。
“这让我们重新拾起了我们国家拥有但已经很久没有使用过的许多技能,”拉普兰特在去年 12 月的里根国防论坛上告诉记者。
美国国防工业专家往往用讲解经济学入门知识的方式来谈论这个行业。他们经常指出,该行业的走势与其他市场截然不同。
国防企业生产政府想要的产品,但很少会超出政府的需求或生产其他产品。因此,五角大楼的订单对执行订单的企业有着非同寻常的影响力。
“国防工业对客户的需求非常敏感,反应也很迅速,”大西洋理事会智库高级研究员史蒂夫·格伦德曼说。
格伦德曼在20世纪90年代的五角大楼工作,正值和平红利时期。在里根政府时期,由于美国与苏联展开竞争,军费开支大幅飙升。但随着1991年苏联解体,冷战结束,美国不再有对手需要超越。据战略与预算评估中心智库的数据显示,从1985年到1998年,美国的国防开支逐年下降。
CSBA发现,在此期间,五角大楼在采购、研究、开发和建设方面的支出下降了44%。
美国需要建立一套和平时期适用的国防工业体系。于是,就有了“最后的晚餐”,这个名字正是奥古斯丁本人为1993年的那次晚宴所起的。他当时就表示,这似乎是一项明智的政策。国防开支势必会下降,五角大楼面临两个选择:要么建立一个规模庞大的国防工业体系,要么建立一个规模更小、效率更高的体系。
国防部官员鼓励后一种做法。随着主要承包商数量的锐减,中小型供应商的数量也大幅下降,因为企业为了降低成本而纷纷合并。
最终,政府忍无可忍。20世纪90年代末,政府否决了洛克希德·马丁公司收购诺斯罗普·格鲁曼公司的计划。大规模并购的时代就此结束。
其影响体现在两个方面:竞争减少和快速反应能力下降。前者在很多情况下意味着五角大楼的订单处理时间更长、成本更高,而且更容易受到脆弱供应链的影响。后者——既是整合的结果,也是由于制造技术效率的提高——使得应对突发冲突变得更加困难。
进入21世纪,各国领导人开始倾向于选择更先进但数量较少的武器。国防部长唐纳德·拉姆斯菲尔德称之为“转型”,认为这将使五角大楼的武器库领先一代人。
其中一些先进武器——例如陆军的未来作战系统和海军的濒海战斗舰——并未达到预期效果。而向更少但更强大的系统转型,进一步促使各公司进行合并。
1998年,有五家公司建造水面舰艇,两家公司生产履带式战车。到2020年,这两个数字分别下降到两家和一家。
五角大楼报告称,美国履带式战车制造商的数量从1990年的3家下降到2020年的1家。2023年1月5日,通用动力公司的一名员工正在引导一辆M1A2坦克从火车上卸下。(美国陆军参谋军士拉基姆·卡特摄)
“虽然听起来很愚蠢,但考虑到我们在国防上的花费,通常情况下,任何单一供应商的采购量都不够,”退役陆军中将戴夫·巴塞特说道,他直到去年12月才卸任国防合同管理署署长一职。
和平红利并未在美国发动的伊拉克和阿富汗战争后得以延续。
9·11事件以及随后的两次冲突导致国防部预算大幅增加。据CSBA统计,经通货膨胀调整并计入补充拨款后,五角大楼的支出在1999财年至2008财年期间平均增长了7%。
这笔支出用于应对一系列新的威胁。
例如,巴塞特和其他接受《防务新闻》采访的专家特别提到了一类为战争而开发的重型装甲车辆。防地雷反伏击车(MRAP)项目是国防部长罗伯特·盖茨的首要任务。五角大楼投入巨资,在三年内交付了超过13000辆MRAP车辆。
该项目后来成为一些人的象征,他们认为只要给予适当的资源,国防工业就能灵活行动。但它也提醒人们,过去15年多来,这些资源都用在了哪里。从2001年开始,五角大楼就需要用于反叛乱的武器。
这些远远不足以抵御俄罗斯的进攻——一场以火炮和小型无人机为特征的工业时代战争。而保卫台湾的需求则更为迫切,台湾是一个岛屿国家,正受到一个领先的制造业强国的威胁。
“如果你面临的是伊拉克的威胁,那么你的应对能力可能不如面对俄罗斯和中国的威胁时那么强,”奥巴马政府时期的国防部副部长、现任 Leonardo DRS 首席执行官比尔·林恩说道。
国防官员们已经清楚地认识到了能力的变化。
布雷特·兰伯特曾在林恩担任副部长期间负责五角大楼的工业基础政策,他回忆起 2011 年袭击密苏里州乔普林的一场龙卷风——几乎袭击了一家主要的电池供应商。
2011年5月,一场致命的龙卷风袭击了密苏里州乔普林市。(图片来源:Brendan Smialowski/AFP via Getty Images)
兰伯特说:“我们意识到,即使工厂本身没有受到冲击,我们也没有备用方案。这对我来说是一个警钟。”
兰伯特曾参与领导一项针对主要武器项目的四年研究,该研究也发出了另一项警告。他发现,很大程度上,主承包商并不了解自身的供应链。
但前五角大楼工业官员罗伯特·卢萨迪表示,尽管警报响起,却无人应答。他指出,这项研究的数据大多湮没在历史长河中。
“没人用过它,”他说。
“从来不只有一个问题”
2017 年夏天,埃里克·丘宁和家人在外滩群岛度假。
当时身为麦肯锡咨询公司合伙人的丘宁,正和孩子们坐在北卡罗来纳州的海滩上,一边浏览手机,一边看到一条关于一项行政命令的新闻稿。唐纳德·特朗普总统正在指示五角大楼自艾森豪威尔政府以来首次对其国防工业基础进行自上而下的审查。
“我心想:‘他们会找谁来做这件事呢?’”丘宁在接受《防务新闻》采访时说道。
当天晚些时候,他正从海滩往回走,突然接到五角大楼的电话,询问他是否愿意面试负责工业基础政策的最高职位。10月份,他接受了这份工作,这意味着他将负责领导这项研究。
丘宁说:“我们当时的想法是:我们现在该如何全面地从9/11事件后的战争模式(当时我们拥有足够的物质能力,这一点毋庸置疑)过渡到与经济实力相当的国家竞争的模式?”
他发现这样做并不容易——很大程度上是因为美国劳动力市场面临的困境。到上世纪90年代国防工业整合之时,美国制造业已经经历了数十年的严重衰退。
根据丘宁领导的一项研究,从20世纪70年代末到2017年,美国制造业岗位减少了710万个,占该行业劳动力的36%。这种下滑趋势对任何试图迅速壮大美国国防工业的努力都构成了挑战。即使拥有更加先进、高度依赖机器人技术的工厂,武器制造仍然需要懂得如何制造它们的人员。
退役陆军上将巴塞特表示,这正是产能一旦耗尽就难以补充的部分原因。正如全国各地的公司在近期劳动力市场紧张的情况下所经历的那样,寻找和培训技术工人需要数年时间。
在担任国防合同管理署署长期间,巴塞特研究了一些有助于预测制造问题的企业特征。他发现一个重要的特征是工龄不足一年的蓝领员工比例;他表示,一旦这一比例达到一定阈值,质量问题几乎不可避免。
尽管2018年的研究促成了一些改革,但并未扭转制造业的颓势,反而随着新冠疫情期间老员工的大规模退休而雪上加霜。与华盛顿的许多报告一样,该研究指出了诸多重大问题,这些问题与其他困难并存,都在争夺时间和资金。
2020年4月21日,在华盛顿州伦顿市,波音737 Max飞机组装厂在新冠疫情爆发后重新开放不久,一名工人离开工厂。(Stephen Brashear/Getty Images)
“从来不会只有一个问题,”现任造船企业HII副总裁的丘宁说。“最紧迫的问题总是最受关注。”
到2022年,问题已经变得迫在眉睫。俄罗斯对乌克兰发动了全面入侵,而华盛顿则继续向基辅提供武器援助。
自2022年2月以来,美国已向乌克兰提供了数额惊人的安全援助——超过440亿美元。尽管金额如此巨大,但五角大楼许多人从中吸取的教训之一是,乌克兰工业界对危机准备不足。
可以说,这一点在美国155毫米炮弹的供应中体现得最为明显。
155毫米炮弹——以及小型无人机——已经成为乌克兰战争格局的重要组成部分。卡内基国际和平基金会分析师迈克尔·科夫曼告诉《防务新闻》,基辅每月需要6万至8万发炮弹用于自卫。
这一速度远远超过了乌克兰西方盟友的补给速度。五角大楼负责采购和保障的拉普兰特表示,即使国会在2023年额外拨款15亿美元用于提高产量,美国在12月份也只生产了2.8万至3万枚炮弹。
美国国防部的目标是到 2025 年年中实现每月 10 万发子弹的产量。但如果没有国会的更多拨款,这一速度可能无法实现,而国会已经搁置了白宫要求的一项安全支出法案。
但近年来,资金投入并未减缓生产速度;据CSBA称,从2016财年到2023财年,国会向白宫申请的五角大楼采购基金增加了7.3%,即793亿美元。问题在于需求不稳定,拉普兰特去年秋天用另一张图表说明了这一点。
从 30 年前的海湾战争开始,军火订单经历了起伏波动:危机爆发,五角大楼大幅增加供应,几年后达到目标数量,然后危机消退,供应下降。
“这是我们现在面临的挑战之一——由于我们历史上对工业基础的投资不足,导致我们无法做出调整,”五角大楼工业基础发展负责人贾斯汀·麦克法林告诉《防务新闻》。
军需品往往极易受到这种“鞭打效应”的影响。埃里克·范宁曾在海军、空军和陆军担任多年高级职务,他注意到了这种模式。各军种的大部分预算都集中在大型系统上,例如航空母舰和战斗机。为了控制预算,一些价格较低的项目最终被削减。而且,由于五角大楼的需求会影响供应,因此履行这些订单的公司也逐渐缩减了产能。
2023年4月13日,在宾夕法尼亚州斯克兰顿陆军弹药厂,数枚155毫米炮弹在生产过程中被储存起来。(Matt Rourke/AP)
如今订单再次激增——这次是155毫米炮弹和其他一系列弹药。国会已允许五角大楼为部分弹药签订长期合同,从而确保未来几年需求稳定。但据现任航空航天工业协会主席范宁称,其他一些公司则担心政府需求无法持续。
他说:“那种长期承诺的感觉还没有完全形成。”
“与敌人的首次接触”
五角大楼表示,其新的工业基础战略表明了未来的承诺。该文件重点关注四个领域:构建具有韧性的供应链、确保劳动力随时待命、制定有利于企业的采购政策以及加强国家安全市场。
“这些并非新观点,”工业基础政策代理副部长哈利玛·纳吉布-洛克告诉《防务新闻》,“但它们一直缺乏必要的权威性。”
今年1月,纳吉布-洛克在另一次记者会上概述了五角大楼未来三到五年国防工业基地的发展目标。其中一项是加快生产周期较长的零部件,例如滚珠轴承或固体火箭发动机,这些零部件会拖慢重要武器的生产速度。其他目标包括改造供应链中过时的环节,以及更多地利用《国防生产法》的资金。《国防生产法》允许五角大楼发放与国家安全相关的拨款。
“我们不能再忽视(工业基础方面的问题)并寄希望于情况好转了,”纳吉布-洛克告诉《防务新闻》,“我们必须采取果断行动。”
但有些问题是五角大楼无法控制的。
首先是政治因素。截至发稿时,国会尚未通过完整的国防开支法案——这是十多年来一系列持续拨款决议中的最新一项。国防问题在很大程度上仍然是一个两党共识,但共和党内部的分歧正在扩大——这也是国会迟迟未能通过对乌克兰、以色列和台湾的额外援助的原因之一。
参议院军事委员会资深成员、密西西比州共和党参议员罗杰·威克在一份声明中告诉《防务新闻》:“当今的安全环境要求我们大幅、长期地增加国防资源。”
2024年1月11日,密西西比州共和党参议员罗杰·威克在参议院共和党人举行的新闻发布会上发表讲话。(图片来源:Andrew Caballero-Reynolds/AFP via Getty Images)
他在众议院的一些同事则持怀疑态度。“美国人民辛勤工作挣来的每一分钱,但国防部似乎已经成为挥霍这些资金的行家,而且毫不眨眼,”威斯康星州共和党众议员格伦·格罗特曼在12月接受《防务新闻》采访时表示。
第二个外部问题是创新。前国防部副部长林恩表示,几十年前,五角大楼一直处于新技术发展的前沿——例如GPS或互联网。但如今,它却发现自己处于下游,目前人工智能和无人机领域的许多进步都来自商业领域。
学习如何更好地与这些公司合作是该战略的目标之一。纳吉布-洛克表示,要做到这一点,就需要更新五角大楼的采购政策,使其更好地与商业领域——五角大楼对这个市场的影响力较小——保持一致。
“由于技术的快速变革,我们对需要时会有哪些东西存在的许多假设,在某些情况下都被证明是夸大其词的,”纳吉布-洛克说。
第三个挑战来自美国的对手。俄乌战争和以哈战争提醒我们,竞争对手最终决定了美国国防工业必须以多快的速度运转,以及何时运转。
克里斯·米基恩齐在五角大楼从事工业基础政策工作期间吸取了这一教训。她曾协助制定该部门的工业政策,并亲眼目睹了各种挑战的演变,前后长达八年之久。2022年乌克兰战争爆发时,她是少数几位负责对基辅提供援助的官员之一。
过去30年的许多问题都暴露无遗。她举例说,工人短缺阻碍了关键军火的快速生产。
“该部门得到了它出资建设的产业基础,”她说。
米基恩齐去年夏天离职。今年1月,《防务新闻》采访了负责五角大楼工业基地发展的麦克法林,采访地点就在米基恩齐以前的办公室——一个狭小、没有窗户的隔间。
由于无人入住,该空间被改造成了会议室——这对麦克法林向各公司介绍政府新战略很有帮助。
麦克法林说:“我从小就听过这样一句谚语:计划赶不上变化。我们可以制定计划,但我们也必须能够灵活调整。”
诺亚·罗伯逊是《防务新闻》的五角大楼记者。他此前曾为《基督教科学箴言报》报道国家安全新闻。他拥有弗吉尼亚州威廉斯堡威廉与玛丽学院的英语和政治学学士学位。