If Washington is going to be a shareholder, it should act like one如果华盛顿要成为股东,就应该像个股东那样行事。
As governments increasingly seek to broaden industrial advantages, if the US is going to follow suit, its justifications should be clear, exceptional and subject to consistent rules, two advisors argue.
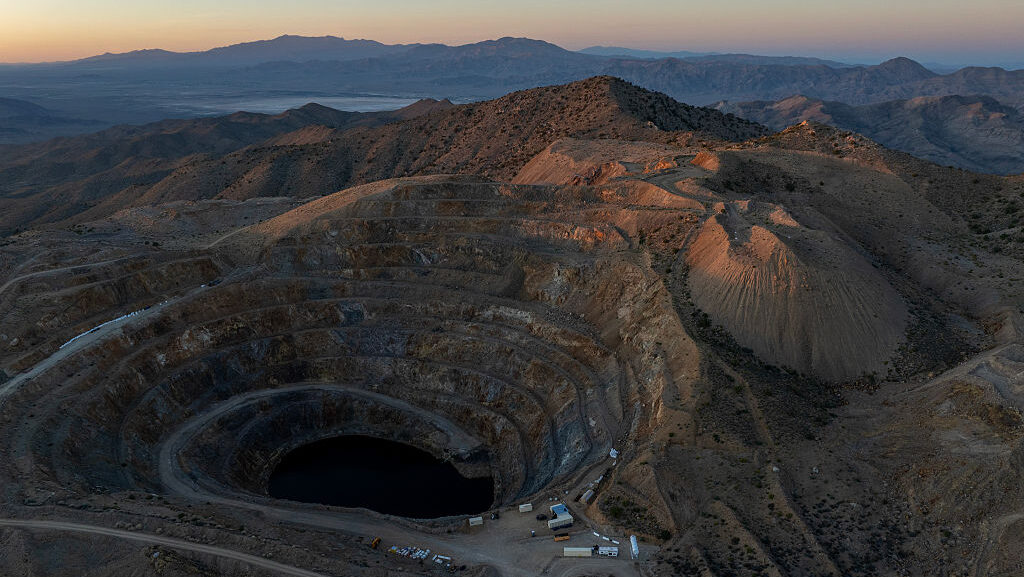
The once-disused Colosseum Mine inside the Mojave National Preserve is being prepared to become North America's second active rare earth minerals mine. (Photo by David McNew/Getty Images)
For most of modern American economic history, Washington avoided behaving like an investment fund. The government regulates companies, taxes them, buys from them, lends to them and subsidizes activities it considers strategically important, but owning pieces of individual companies has generally been reserved for development finance, financial crises and other exceptional circumstances.
That boundary is now eroding. Since January 2025, the US government has announced $27.7 billion across 39 transactions involving direct ownership or equity-like stakes, according to the Council on Foreign Relations’ US Government Deal Trackers . The investments span critical minerals, semiconductors, manufacturing, infrastructure and other strategic sectors.
The rationale is not difficult to understand. Economic security and national security increasingly overlap, and China dominates important parts of critical-mineral processing and other strategic supply chains. Governments around the world are using subsidies, state-owned companies, export restrictions and other forms of intervention to secure industrial advantage. In that environment, there are circumstances in which the US government putting capital at risk alongside private investors can help unlock a strategically important project.
But not every strategic problem needs the federal government on the share register. Government is poorly equipped to behave like a conventional investment manager, and public capital should not substitute for private investment where markets can reasonably deliver the same outcome.
If Washington is going to assume equity risk, the case for doing so should be clear, exceptional and subject to consistent rules.
Any government equity play should follow a disciplined assessment of whether alternative support mechanisms, such as a loan, guarantee, offtake agreement, procurement contract, or conventional subsidy, could achieve the objective more effectively. If government capital is deemed necessary to bridge the gap where private capital returns may be unmet, this intervention requires rigorous due diligence on company selection and valuation, alongside a clear understanding of the strategic benefit to the government.
Crucially, to address what happens when private capital is eventually ready and willing to take over, the government must establish a clear exit strategy for itself. Such rigor in planning the eventual off-ramp for government capital is especially important where Washington is simultaneously acting as a shareholder, regulator, customer, or policymaker.
Island surge: the Army’s Next Generation Command and Control in action
Lightning Surge exercises are turning soldier feedback on NGC2 into operational software changes in days, not years.
Recent critical-minerals deals show how quickly the boundaries are shifting. The Pentagon’s $400 million investment in MP Materials combined equity with loans, price support and an offtake agreement, while the Department of Energy took warrants in Lithium Americas and its Thacker Pass joint venture as part of a restructuring intended to reduce taxpayer risk. Equity is becoming another tool of US industrial policy, often layered onto other forms of public support. That makes rigorous investment and governance standards more important, not less.
The issue becomes particularly acute when Washington invests in foreign companies, in some cases, repeatedly . If the federal government is going to invest taxpayer money abroad, it should establish governance expectations comparable to those it would expect when investing in an American public company. That means appropriate independent oversight, credible audit arrangements, scrutiny of related-party transactions, protections against inappropriate dilution, transparent financial reporting and meaningful remedies when agreed governance standards are breached.
It does not mean that American investment should automatically subject a foreign company to the full reach of American corporate or securities law. Different jurisdictions have different corporate structures, and credible governance systems need not be American per se. But American public investment should carry credible investor protections, just as any sophisticated institutional investor would consider before committing substantial capital.
Washington already negotiates such protections in some deals. When it invested in Canada-based Trilogy Metals, the US government negotiated the right to designate an independent third-party director and, subject to its continuing shareholding, a non-voting board observer. It also obtained a consent right over certain very large increases in indebtedness.
The question is why such protections should be reinvented transaction by transaction. As federal equity investment becomes more common, agencies should establish a baseline set of governance principles for investments in foreign companies. Those principles should be adaptable to the circumstances of a transaction rather than mechanically exporting US securities regulation overseas. But at minimum, federal equity investments in foreign companies should carry a baseline set of governance protections covering independent board and audit oversight, related-party transactions, dilution, disclosure and the government’s rights when governance standards deteriorate.
Robust protections are better for taxpayers, but also fairer to American companies. A US company raising capital on an American exchange operates within a demanding framework of disclosure, audit and corporate-governance requirements. It would be an odd form of industrial policy if a foreign competitor could receive preferential US taxpayer capital while facing materially weaker safeguards over how that capital and the company itself are governed.
Clear rules also benefit the recipients of government investment by reducing uncertainty. They make it easier for companies to understand what accepting federal capital entails and harder for individual transactions to become exercises in political bargaining.
More importantly, they could make strategic industrial policy more durable. An investment whose purpose, valuation and protections are transparent is easier to defend to Congress, auditors, future administrations and taxpayers. One negotiated hurriedly behind closed doors is easier to characterize as favoritism for a subsequent administration to unwind.
There is a danger in allowing the debate over governance to obscure the more fundamental question of when the US government should own companies at all. The test should be whether government ownership solves a specific problem that less intrusive instruments cannot, and whether the prospective public return adequately compensates taxpayers for the additional risk.
The Trump administration has clearly rediscovered equity as an instrument of economic statecraft, and the US government is already a shareholder in companies beyond its borders. The practical challenge is therefore to make it a more disciplined one. That starts with due diligence before the investment, clarity about what public ownership is supposed to achieve, transparent criteria for choosing recipients, a credible route eventually to exit and governance protections appropriate to the risks taxpayers are being asked to bear.
Washington should not behave like a political patron dispensing capital to favored companies. Nor should it be a passive shareholder willing to accept protections that a sophisticated private investor would reject. If the US government is going to invest like an institutional investor, it should govern its investments like one too.
Phillip Cornell is managing director of ASIO Energy LTD, senior energy advisor at the Economist, and a senior fellow at the Atlantic Council. He was previously senior advisor to the chairman and CEO of Saudi Aramco and to the head of the International Energy Agency.
Stephen Rodriguez is a defense investor at DCVC. He is also founder of One Defense and a senior advisor at the Atlantic Council.
位于莫哈韦国家保护区内的废弃的科洛西姆矿正在进行改造,有望成为北美第二座仍在开采的稀土矿。(图片来源:David McNew/Getty Images)
在现代美国经济史的大部分时期,华盛顿都避免扮演投资基金的角色。政府监管企业、向企业征税、从企业采购、向企业贷款,并补贴其认为具有战略意义的活动,但持有个别企业的股份通常仅限于发展融资、金融危机和其他特殊情况。
如今,这一界限正在逐渐模糊。据美国外交关系委员会的美国政府交易追踪数据显示,自2025年1月以来,美国政府已宣布了39项交易,总额达277亿美元,涉及直接所有权或类似股权的投资。这些投资涵盖关键矿产、半导体、制造业、基础设施和其他战略领域。
其逻辑不难理解。经济安全与国家安全日益交织,而中国在关键矿物加工和其他战略供应链的重要环节占据主导地位。世界各国政府都在利用补贴、国有企业、出口限制和其他干预手段来确保产业优势。在这种环境下,美国政府与私人投资者共同承担风险并投入资金,在某些情况下可以帮助启动具有战略意义的项目。
但并非所有战略问题都需要联邦政府介入。政府并不擅长扮演传统投资管理者的角色,在市场能够合理实现相同结果的情况下,公共资本不应取代私人投资。
如果华盛顿要承担股权风险,那么这样做的理由应该是明确的、特殊的,并且要遵守一致的规则。
任何政府股权投资都应在经过严谨评估后进行,以确定是否存在其他更有效的支持机制,例如贷款、担保、承购协议、采购合同或传统补贴。如果认为政府资本对于弥补私人资本回报可能不足的缺口是必要的,那么这项干预措施需要对公司选择和估值进行严格的尽职调查,并充分理解其对政府的战略益处。
至关重要的是,为了应对私人资本最终准备就绪并愿意接管时可能出现的情况,政府必须为自身制定清晰的退出策略。当华盛顿同时扮演股东、监管者、客户和政策制定者等角色时,这种对政府资本最终退出途径的严谨规划尤为重要。
岛屿突击:陆军下一代指挥控制系统的实战演练
“闪电突击”演习将士兵对 NGC2 的反馈转化为几天内(而不是几年内)的操作软件变更。
近期关键矿产交易表明,相关领域的边界正在迅速变化。五角大楼对MP Materials的4亿美元投资,结合了股权、贷款、价格支持和承购协议;与此同时,能源部通过重组计划,获得了Lithium Americas及其Thacker Pass合资企业的认股权证,旨在降低纳税人的风险。股权正成为美国产业政策的又一工具,通常与其他形式的公共支持相结合。这使得严格的投资和治理标准显得更加重要,而非不那么重要。
当华盛顿投资外国公司,有时甚至是反复投资时,这个问题就变得尤为尖锐。如果联邦政府要将纳税人的钱投资到海外,就应该建立与投资美国上市公司时同等的治理预期。这意味着适当的独立监督、可信的审计安排、对关联方交易的审查、防止不当稀释的保护措施、透明的财务报告,以及在违反既定治理标准时采取有效的补救措施。
这并不意味着美国投资就应该自动使外国公司完全受美国公司法或证券法的约束。不同的司法管辖区有着不同的公司结构,可靠的治理体系本身并不一定非得是美国的。但是,美国的公共投资应当提供可靠的投资者保护,正如任何成熟的机构投资者在投入大量资金之前都会考虑的那样。
华盛顿已经在一些交易中协商过此类保护措施。例如,美国政府投资总部位于加拿大的Trilogy Metals公司时,就曾协商过指定一名独立第三方董事的权利,以及在持续持股的前提下,指定一名无投票权的董事会观察员。此外,美国政府还获得了对某些巨额债务增长的同意权。
问题在于,为何此类保护措施需要逐笔交易地重新制定。随着联邦股权投资日益普遍,各机构应为投资外国公司制定一套基本的公司治理原则。这些原则应能根据交易的具体情况进行调整,而非机械地将美国证券监管法规照搬到海外。但至少,联邦对外国公司的股权投资应具备一套基本的公司治理保护措施,涵盖独立董事会和审计监督、关联方交易、股权稀释、信息披露以及公司治理标准恶化时政府的权利。
强有力的保护措施不仅对纳税人更有利,对美国公司也更公平。一家在美国证券交易所筹集资金的美国公司,必须遵守严格的信息披露、审计和公司治理要求。如果一家外国竞争对手能够获得美国纳税人提供的优惠资金,却面临着远低于美国公司在资金和公司治理方面所受到的保护,那将是一种非常奇怪的产业政策。
明确的规则也有利于政府投资的接受者,因为它能减少不确定性。规则使企业更容易理解接受联邦资本意味着什么,也使个别交易更难沦为政治博弈。
更重要的是,它们可以使战略性产业政策更具可持续性。一项目的、估值和保障措施都透明的投资更容易向国会、审计人员、未来的政府和纳税人进行辩护。而一项在闭门会议中匆忙达成的投资则更容易被认定为偏袒行为,从而让后续政府不得不予以撤销。
如果围绕公司治理的争论掩盖了美国政府何时应该拥有公司这一更为根本的问题,那就存在风险。检验标准应该是:政府所有权能否解决其他干预性较小的手段无法解决的具体问题,以及预期的公共回报是否足以补偿纳税人承担的额外风险。
特朗普政府显然重新将股权视为经济治国的工具,而美国政府也已持有境外公司的股份。因此,实际的挑战在于如何使股权投资更加规范。这首先需要在投资前进行尽职调查,明确公共所有权的目标,制定透明的受益者选择标准,建立可信的最终退出机制,以及提供与纳税人承担的风险相匹配的治理保障。
华盛顿不应扮演政治庇护者的角色,向其青睐的公司输送资金。它也不应成为被动的股东,甘愿接受那些老练的私人投资者会拒绝的保护措施。如果美国政府要像机构投资者那样进行投资,就应该像机构投资者那样管理其投资。
菲利普·康奈尔是ASIO能源有限公司的董事总经理、《经济学人》的高级能源顾问以及大西洋理事会的高级研究员。他此前曾担任沙特阿美董事长兼首席执行官和国际能源署署长的资深顾问。
斯蒂芬·罗德里格斯是DCVC的国防投资者,同时也是One Defense的创始人,以及大西洋理事会的高级顾问。