Instead of a lump sum EPF withdrawal, how an automatic annuity with opt-out option could work for Malaysians对于马来西亚人来说,与其一次性提取公积金,不如考虑一种带有退出选项的自动年金方案。
KUALA LUMPUR, Oct 22 — Licensed financial planner Rajen Devadason said an insurance annuity scheme like Singapore’s CPF LIFE could also work in Malaysia.He explained that if...
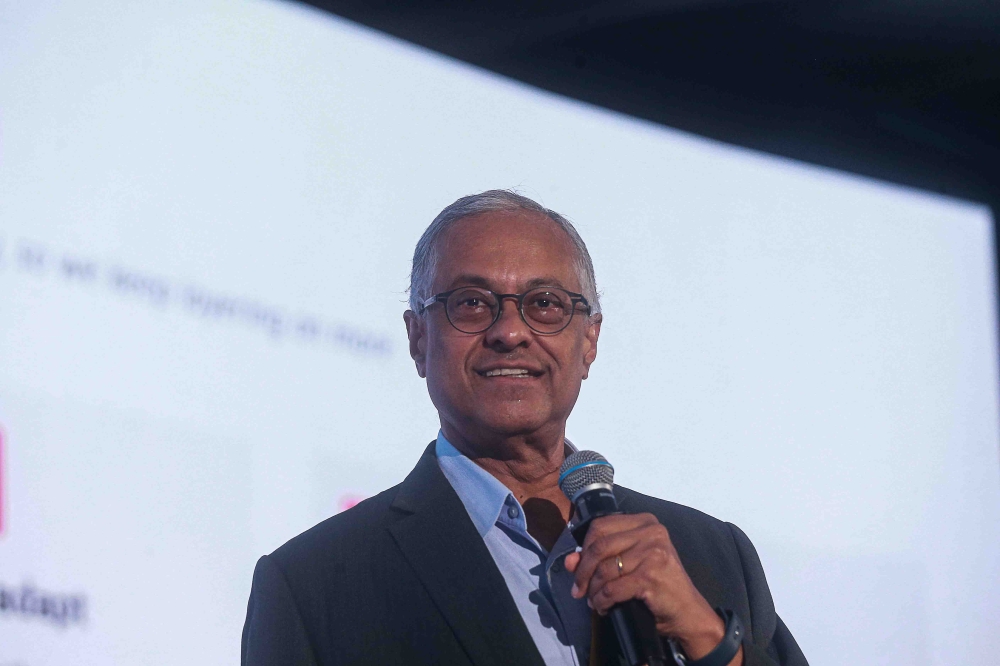
At the International Social Wellbeing Conference 2026, financial planner Rajen Devadason suggested that Malaysia could benefit from an insurance annuity scheme similar to Singapore's CPF LIFE, provided it includes an opt-out option and allows current EPF withdrawal parameters.
He emphasized the importance of combining such schemes with individual responsibility for private pension building and extended working years, to enhance retirement savings and passive income sources.
Senior social protection specialist, Mariko Ouchi, noted that there is no universal retirement model, emphasizing the need for country-specific solutions and the importance of regular evaluations of pension systems to adapt to changing demographics and work patterns.
KUALA LUMPUR, Oct 22 — Licensed financial planner Rajen Devadason said an insurance annuity scheme like Singapore’s CPF LIFE could also work in Malaysia.
He explained that if the government gives a long runway, and make it politically more palatable by giving people a chance to opt out, a similar scheme may be acceptable.
He was speaking to Malay Mail at the sidelines of the recent Employees Provident Fund’s (EPF) International Social Wellbeing Conference 2026 (ISWC 2026).
Rajen said there might be the risk of a political backlash if access or withdrawals from EPF savings at ages 50, 55 and 60 is changed so one possibility is to keep the same withdrawal rules while using a small portion of EPF savings for an annuity.
“But if let’s say you increase your retirement age to 65 and you don’t change the withdrawal parameters at 50, 55, and 60, people are cool, no problems.
“But if you then give people the opportunity to work longer, that funding between 60 and 65, if all of that flowed into an annuity, that might work, might help,” he added.
Rajen believes something like an annuity insurance would be a “step in the right direction” for Malaysia, based on global experience.
“But by itself, it’s not enough. People must take personal responsibility. They have to build their own private pensions,” he said, adding that this should run in parallel with working longer.
“The whole purpose of working longer is that you can build a higher pile of retirement savings,” he said, also saying these funds should be used as capital to create multiple streams of passive income for retirement.
No ‘one size fits all’ when designing retirement or pension systems
International Labour Organisation’s (ILO) senior social protection specialist for South Asia Mariko Ouchi said there is no “one perfect model” or “one fit for all” pension model in the world.
“Many people ask me what is the best model or good practice in terms of pension and old-age benefit in the world. And then I answer, all countries are having problems in one way or another. So, there is no ‘one perfect model’ as such,” she said in her presentation at the ISWC 2026.
She said each country will have to find solutions best suited to their different circumstances: “Malaysia has to seek its own solution to provide the best income guarantee for the elderly people.”
Ouchi said countries go through many changes, such as the different work nature including international jobs done remotely; migration; demography; higher life expectancies; higher retirement ages; and higher pension access ages.
She added it is important for countries to carry out periodic reviews or periodic actuarial evaluation on a country’s old-age benefit model (such as every three years or every five years) depending on the country and its system’s stability.
Countries also need to carry out a mid-term to long-term revisiting of their existing pension models, to see if it could continue running for decades unchanged or if substantial reforms are needed, Ouchi explained.
Recommended reading:
How Malaysia can raise its retirement age from 60 to 65: Experts explain the math and more
EPF’s i-Emas monthly payouts could help retirees avoid burning through savings
Make your EPF savings go the distance: Smart tips for retirement at 55 and beyond
As Singaporeans live longer, a look at how they manage their retirement savings
How Malaysians can have enough money after retiring: Moving away from choosing EPF ‘lump sum’ payouts
Haze or ship fumes? Maritime experts want closer watch on vessel emissions at Malaysian ports
在 2026 年国际社会福祉大会上,理财规划师 Rajen Devadason 建议,如果马来西亚的保险年金计划类似于新加坡的 CPF LIFE,并且包含退出选项,允许当前的 EPF 提款参数,那么马来西亚可以从中受益。
他强调,应将此类计划与个人承担私人养老金积累责任和延长工作年限相结合,以增加退休储蓄和被动收入来源。
高级社会保障专家大内真理子指出,目前没有普遍适用的退休模式,强调需要制定针对特定国家的解决方案,并定期评估养老金制度以适应不断变化的人口结构和工作模式的重要性。
吉隆坡,10 月 22 日讯——持牌理财规划师 Rajen Devadason 表示,类似新加坡 CPF LIFE 的保险年金计划在马来西亚也可能行得通。
他解释说,如果政府给予较长的过渡期,并通过给予人们选择退出的机会使其在政治上更容易被接受,那么类似的方案或许是可以接受的。
他是在最近举行的雇员公积金局 (EPF) 2026 年国际社会福祉大会 (ISWC 2026) 的间隙接受《马来邮报》采访时发表上述言论的。
Rajen表示,如果改变50岁、55岁和60岁时提取公积金储蓄的规则,可能会引发政治反弹,因此一种可能性是保持相同的提取规则,同时将公积金储蓄的一小部分用于年金。
“但是,假设你将退休年龄提高到 65 岁,并且没有改变 50 岁、55 岁和 60 岁时的提款参数,人们就不会介意,也不会有问题。
“但是,如果你让人们有机会延长工作时间,那么60岁到65岁之间的所有资金,如果全部流入年金,那或许可行,或许会有帮助,”他补充道。
根据全球经验,拉詹认为类似年金保险这样的产品对马来西亚来说是“朝着正确方向迈出的一步”。
“但这本身还不够。人们必须承担个人责任。他们必须建立自己的私人养老金,”他说道,并补充说,这应该与延长工作年限同时进行。
“延长工作年限的全部意义就在于你可以积累更多的退休储蓄,”他说道,并表示这些资金应该用作资本,为退休创造多种被动收入来源。
在设计退休或养老金制度时,没有“一刀切”的方案。
国际劳工组织(ILO)南亚高级社会保障专家大内真理子表示,世界上没有“一个完美的模式”或“一个适合所有人的”养老金模式。
“很多人问我,世界上养老金和老年福利方面最好的模式或良好做法是什么。我的回答是,所有国家都存在这样那样的问题。所以,并不存在所谓的‘完美模式’,”她在2026年国际养老金和老年福利大会(ISWC 2026)上发表讲话时说道。
她表示,每个国家都必须找到最适合自身情况的解决方案:“马来西亚必须寻求自己的解决方案,为老年人提供最好的收入保障。”
大内表示,各国正在经历许多变化,例如不同的工作性质(包括远程国际工作)、移民、人口结构、更高的预期寿命、更高的退休年龄和更高的养老金领取年龄。
她补充说,各国应当根据自身情况和制度稳定性,对本国的养老福利模式进行定期审查或定期精算评估(例如每三年或每五年一次)。
大内解释说,各国还需要对现有的养老金模式进行中长期的重新审视,看看这种模式是否可以继续维持数十年不变,或者是否需要进行实质性改革。
推荐阅读:
马来西亚如何将退休年龄从60岁提高到65岁:专家解读计算方法及更多细节
公积金局 (EPF) 的 i-Emas 月度分红可以帮助退休人员避免耗尽积蓄。
让您的公积金储蓄发挥最大效用:55岁及以后退休的明智之选
随着新加坡人寿命延长,让我们来看看他们是如何管理退休储蓄的。
马来西亚人如何才能在退休后拥有足够的钱:不再选择公积金“一次性”领取方式
是雾霾还是船舶废气?海事专家呼吁加强对马来西亚港口船舶排放的监测