Defense firms soar on ample military spending, testing manufacturing schemes国防企业受益于充足的军费开支和测试制造方案而蓬勃发展
For the many billions of dollars governments spend on defense, companies are on the hook to get their production pipelines in place and deliver.
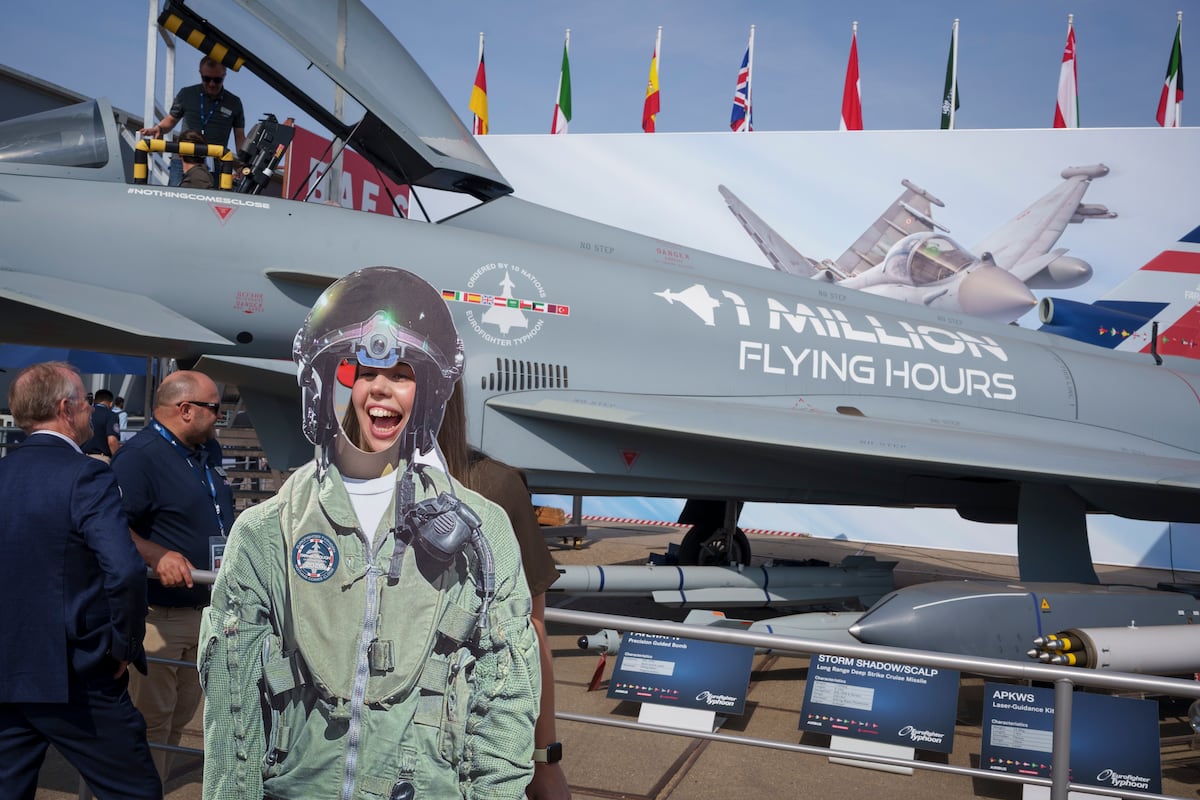
The year 2025 was another record setter for global defense companies, so much so that production bottlenecks in Western nations — not the usual industry lamentations about lacking government spending — began creeping up as the key problem many NATO countries are facing today.
Companies in the United States and Europe rode a wave of significant defense-spending increases on both sides of the Atlantic. In Europe, individual national budget increases, as well as the European Union’s increasing involvement in brokering and financing joint procurement, continued to increase the revenue of defense industry players large and small.
In the United States, the 2025 Reconciliation Act is set to pump most of the legislation’s total $156 billion into acquisition — on top of the regular defense budget of roughly $900 billion for that year.
“Now, it’ll take years for that enacted money to actually flow to the companies and to their financial statements,” said Mark Cancian, a senior adviser in the defense analysis program at the Washington-based Center for Strategic and International Studies. “But it will be a big boost for many companies.”
In Europe, the trajectory is perhaps more immediate, as governments spooked by Russia’s full-scale invasion of Ukraine in February 2022 began dialing up their military expenditures drastically years ago.
Besides absorbing the overall plus-up in the amount of money available, companies on the continent have rewired their business strategies to align with a preference for European-made equipment by many European governments, though the massive influx of cash on all sides obfuscates whether European companies have meaningfully cut into the bottom lines of U.S. defense giants.
More money on both sides of the pond
The latest Defense News Top 100 ranking of global defense companies bears out the overall upward trend, with companies posting higher annual defense revenues, a combined $700 billion compared with $629 billion in the prior year, a 11.3% increase.
The first four spots of our latest ranking continue to be in the hands of U.S. firms, with Lockheed Martin in the top spot with $72.1 billion in annual defense revenue, followed by RTX ($46 billion), General Dynamics ($39.4 billion) and Northrop Grumman ($37 billion), in that order.
Rheinmetall CEO Armin Papperger stands next to a miniature F-35 inside the hall where company workers will begin manufacturing fuselage sections for the F-35 stealth combat jet on July 1, 2025, in Weeze, Germany. (Lukas Schulze/Getty Images)
Britain-based BAE Systems, which has a sizable U.S. operation, is the first non-American company in the lineup, creeping up one spot into number five over last year’s ranking, with $36 billion in revenue reported.
Boeing’s defense segment similarly climbed one position, into slot number six with $35.7 billion in revenue, as did L3Harris ($17.4 billion), which now places eighth.
In between sits a Chinese entrant, Aviation Industry Corporation of China, at $32.3 billion.
On the heels of that company begins a lineup of firms from all over the world, with European outfits continuing to inch upwards — the big players Leonardo, Airbus and Thales placing 9, 10 and 12, respectively.
Perhaps no company represents the European defense uptick as much as Germany’s Rheinmetall, which reported $11.2 billion in 2025 annual revenue, up from $8.3 billion in the previous year. The company now sits at number 15 on the list, up from 18 in the prior year.
The firm has, over the years, branched out its operations into virtually all domains of war — land, air, naval, space, cyber and unmanned — from Europe to Australia, and has embraced the formerly low-brow segment of explosives and ammunition.
That category, which includes artillery shells, missiles and air-defense interceptors, has seen unprecedented demand in all NATO countries, based on the experiences since Russia’s full-scale invasion of Ukraine in February 2022.
Air defense competitions on the rise
The air defense category is also where the biggest shortfalls lie. Companies have expanded their supply chain setups in recent years to build artillery shells, urgently needed in Ukraine to shoot over immediate front lines’ robot-dominated no-go zones for infantry.
But what’s still lacking are sufficient interceptor missiles and drones to defend against Russian missiles fired at Ukrainian cities.
Visitors look at aviation engines displayed in the RTX Corp. pavilion at the Paris Air Show in Paris, France, on June 18, 2025. (Nathan Laine/Bloomberg via Getty Images)
With the Patriot air defense complex — radars, launchers and interceptors — in the hands of U.S. firms, European and Ukrainian officials have begun thinking through alternatives to the scarce equipment.
Offerers include the Israeli companies involved in that country’s anti-missile architecture, with Elbit ranking 21 on the list, Israeli Aerospace Industries at 27 and Rafael at 30, as well as pan-European firm MBDA at 26 and Germany’s Diehl at 58, up from 82 last year.
Companies with a naval shipbuilding portfolio, such as General Dynamics, Huntington Ingalls (ranking 13, at $12.3 billion annual revenue, up from 16) and South Korea’s Hanwha (rank 16, at $10.4 billion, up from 22), have been lifted by a favorable tide of capital-intensive naval modernization projects worldwide.
In the U.S., defense officials and lawmakers have envisioned a new armada of warships and icebreakers, dedicating a whopping $29 billion for shipbuilding in the 2025 Reconciliation Act alone.
“The Biden administration, and now the Trump administration, have just been pouring money into shipbuilding — way beyond what the industry can absorb,” said Cancian. “And then they’re talking about building another shipyard to produce all these ships that have now been funded,” he added, leaving shipbuilders with order books filled into the 2030s or beyond.
Defense spending as an ‘engine’?
Production bottlenecks for defense components, combined with economic woes in civilian industry sectors, have led to some new creative arrangements.
In Europe, some automotive companies and rail car makers have turned their factory floors into production sites for drones and counter-drone equipment.
The rush to re-arm, based on the worry that Russia might try a Ukraine-style attack elsewhere, has prompted political leaders in Europe to tout what they consider secondary economic effects of the defense bonanza.
Defense officials in the U.K. published figures in August, for example, that said the 2024-25 period saw British weapons and ammunition manufacturing jobs rise by 51%, “part of a wider 26,000 increase” in defense-supported roles nationwide.
“The increase underlines defense as an engine for growth and the move towards a resilient industrial base, proving that investment in the U.K.’s security is investment in the U.K.’s prosperity,” reads an Aug. 20 statement by the Ministry of Defence.
Some Turkish companies, meanwhile, representing a country with a government mandate for making defense equipment at home rather than importing it, made the latest Top 100 list again, improving positions in some cases. Aselsan jumped from spot 43 to 40 on roughly $4.5 billion in reported annual revenue, and Roketsan gained seven ranks, on $2.4 billion, landing at spot 64.
Similarly, Polish state-owned armaments group PGZ jumped from rank 54 in 2024 figures to number 41 in the latest accounting, based on $4.4 billion in revenue last year.
The Polish government has set out plans to create one of NATO’s most powerful armies in Europe, and local weapons programs are typically designed to include Warsaw’s go-to producer as a key partner.
A Sea Baby unmanned surface vessel (USV) navigates along the Dnieper River, ahead of the Independence Day anniversary in Kyiv, Ukraine, on Aug. 22, 2026. (Andrew Kravchenko/Bloomberg via Getty Images)
Meanwhile, the collection of Ukrainian defense companies under the umbrella of Ukroboronprom improved their ranking to spot number 36, up from 49 last year, with a reported revenue of $4.6 billion in 2025.
The country’s defense industry over the past years has put the Kyiv government in a position to provide armaments to its forces that the country previously had to import, often with operational limitations attached.
So much has the Ukrainian defense industry gained in expertise that allied militaries are itching to incorporate its know-how into their own supply chains.
Looking ahead, there is more spending expected, and more business for relevant defense companies, in the field of air and missile defense, said Cancian. Much of that will be connected to whatever the Trump administration’s Golden Dome program will entail, he noted.
Golden Dome wildcard
The controversial Golden Dome effort will consist of a sweeping suite of sensors and interceptors — stationed on Earth, in space and everywhere in between — that would make the United States almost impervious to aerial attacks of any kind, the theory goes.
Details have been scant on its exact architecture, and companies are searching for avenues into what they suspect will be a generational chunk of government spending in the hundreds of billions of dollars.
“We still don’t really know what it is,” Cancian said, adding the lack of clarity could make the whole project an increasingly hard sell as time goes by.
On the whole, the analyst said, there is so much defense spending on the books that the U.S. government, for its part, isn’t forced to choose between buying legacy weaponry and new technology.
“The thing that struck me most — I come out at this from a program budget perspective — is that there was enough money to do both,” he said.
Turning the influx of defense money into meaningfully improved defenses will be a top oversight job for politicians. And industry will have to be disciplined to get its ducks in a row to contend with order backlogs and production bottlenecks.
As PricewaterhouseCoopers analyst Scott Thompson noted in a recent performance analysis of the aerospace and defense sectors, “In a market where demand is not the constraint, execution is the differentiator.”
2025 年是全球国防公司又一个创纪录的年份,以至于西方国家的生产瓶颈——而不是通常行业抱怨政府支出不足——开始悄然成为许多北约国家目前面临的关键问题。
美国和欧洲的企业都受益于大西洋两岸国防开支的大幅增长。在欧洲,各国国防预算的增加,以及欧盟在联合采购的协调和融资方面日益增强的参与,持续推高了大大小小的国防工业企业的收入。
在美国,《2025 年预算协调法案》计划将该法案总额 1560 亿美元中的大部分用于采购——这还不包括当年约 9000 亿美元的常规国防预算。
“现在,这笔已颁布的资金需要数年时间才能真正流向各公司并体现在它们的财务报表中,”位于华盛顿的战略与国际研究中心国防分析项目高级顾问马克·坎西安表示。“但这对于许多公司来说将是一个巨大的推动。”
在欧洲,这一趋势或许更为迅速,因为各国政府受到俄罗斯在 2022 年 2 月全面入侵乌克兰的惊吓,早在几年前就开始大幅增加军费开支。
除了吸收可用资金总量的增加外,欧洲大陆的公司还调整了其商业战略,以适应许多欧洲政府对欧洲制造设备的偏好,尽管各方大量资金的涌入掩盖了欧洲公司是否真正蚕食了美国国防巨头的利润。
大西洋两岸的资金都在增加
《防务新闻》最新发布的全球防务公司百强排名证实了整体上升趋势,各公司年度国防收入均有所增长,总计达到 7000 亿美元,而上一年为 6290 亿美元,增长了 11.3%。
在我们最新的排名中,前四名仍然由美国公司占据,洛克希德·马丁公司以721亿美元的年度国防收入位居榜首,其次是RTX(460亿美元)、通用动力(394亿美元)和诺斯罗普·格鲁曼(370亿美元)。
2025年7月1日,在德国韦策,莱茵金属公司首席执行官阿明·帕佩格尔站在一架F-35战机的微缩模型旁,公司员工将在这里开始生产F-35隐形战斗机的机身部件。(卢卡斯·舒尔茨/盖蒂图片社)
总部位于英国的 BAE Systems 公司在美国拥有规模庞大的业务,是榜单上第一家非美国公司,其排名较去年上升一位,位列第五,报告收入为 360 亿美元。
波音公司的国防业务也上升了一位,以 357 亿美元的收入位列第六,L3Harris 公司(174 亿美元)也上升了一位,目前排名第八。
其间还有一家中国企业——中国航空工业集团公司,市值达 323 亿美元。
紧随其后的是来自世界各地的一系列公司,其中欧洲公司继续稳步上升——大型企业莱昂纳多、空客和泰雷兹分别位列第 9、10 和 12 位。
或许没有哪家公司比德国莱茵金属公司更能代表欧洲国防行业的蓬勃发展。该公司公布的2025年年收入预计为112亿美元,高于上年的83亿美元。该公司目前在榜单上排名第15位,比上年上升了1位。
多年来,该公司已将其业务扩展到几乎所有战争领域——陆地、空中、海上、太空、网络和无人领域——从欧洲到澳大利亚,并涉足了以前低端的爆炸物和弹药领域。
该类别包括炮弹、导弹和防空拦截器,根据俄罗斯自 2022 年 2 月全面入侵乌克兰以来的经验,所有北约国家对该类别的需求都达到了前所未有的水平。
防空竞争日益激烈
防空领域也是最薄弱的环节。近年来,各公司纷纷扩大供应链规模,以生产乌克兰急需的炮弹,用于越过前线由机器人控制的步兵禁区。
但目前仍然缺乏足够的拦截导弹和无人机来防御俄罗斯向乌克兰城市发射的导弹。
2025年6月18日,在法国巴黎举行的巴黎航展上,参观者在RTX公司展馆内观看展出的航空发动机。(Nathan Laine/Bloomberg via Getty Images)
由于“爱国者”防空系统(雷达、发射器和拦截器)掌握在美国公司手中,欧洲和乌克兰官员已经开始考虑稀缺设备的替代方案。
投标者包括参与以色列反导体系建设的以色列公司,其中埃尔比特系统公司排名第 21 位,以色列航空航天工业公司排名第 27 位,拉斐尔公司排名第 30 位;泛欧公司 MBDA 排名第 26 位;德国迪尔公司排名第 58 位,比去年的 82 位有所上升。
拥有海军造船业务的公司,例如通用动力公司、亨廷顿英格尔斯公司(排名第 13 位,年收入 123 亿美元,较上年同期上升 16 位)和韩国韩华公司(排名第 16 位,年收入 104 亿美元,较上年同期上升 22 位),都受益于全球资本密集型海军现代化项目的有利浪潮。
在美国,国防官员和立法者设想建造一支新的军舰和破冰船舰队,仅在 2025 年的《预算协调法案》中就拨款高达 290 亿美元用于造船。
坎西安表示:“拜登政府,以及现在的特朗普政府,一直在向造船业投入巨资——远远超过了该行业的承受能力。”他补充道:“然后他们还在讨论建造另一座造船厂来生产所有这些已经获得资助的船舶。”这导致造船商的订单排到了2030年代甚至更久以后。
国防开支能否成为经济的“引擎”?
国防零部件生产瓶颈,加上民用工业部门的经济困境,导致了一些新的创造性安排。
在欧洲,一些汽车公司和铁路车辆制造商已将他们的工厂车间改造成无人机和反无人机设备的生产基地。
由于担心俄罗斯可能会在其他地方发动类似乌克兰的袭击,欧洲各国纷纷加快重新武装,这促使欧洲政治领导人大肆宣扬他们认为国防大采购带来的次要经济效益。
例如,英国国防官员在 8 月份公布的数据显示,2024-2025 年期间,英国武器和弹药制造行业的就业岗位增加了 51%,这是全国国防支持岗位增加 26,000 个“更广泛的增长”的一部分。
英国国防部在8月20日的一份声明中表示:“此次增长凸显了国防作为经济增长引擎的作用,以及向更具韧性的工业基础迈进的趋势,证明对英国安全的投资就是对英国繁荣的投资。”
与此同时,一些土耳其公司再次跻身最新百强榜单,部分公司排名甚至有所提升。土耳其政府要求国防装备自主生产,而非依赖进口。阿塞尔桑公司(Aselsan)的年收入约为45亿美元,排名从第43位跃升至第40位;罗克特桑公司(Roketsan)的年收入为24亿美元,排名上升7位,位列第64位。
同样,波兰国有军火集团 PGZ 的排名从 2024 年预测的第 54 位跃升至最新统计的第 41 位,其去年的收入为 44 亿美元。
波兰政府制定了计划,要打造欧洲北约最强大的军队之一,而当地的武器计划通常会将华沙的主要生产商作为关键合作伙伴。
2026年8月22日,在乌克兰基辅独立日纪念日到来之际,一艘“海宝贝”无人水面艇(USV)沿第聂伯河航行。(Andrew Kravchenko/Bloomberg via Getty Images)
与此同时,乌克兰国防工业公司(Ukroboronprom)旗下的乌克兰国防企业集团排名上升至第 36 位,较去年的第 49 位有所提升,据报道,该公司 2025 年的收入将达到 46 亿美元。
过去几年,该国的国防工业使基辅政府能够向其军队提供该国以前不得不进口的武器装备,而且这些武器装备往往附带操作限制。
乌克兰国防工业积累了如此多的专业技术,以至于盟军都渴望将其技术诀窍融入到自己的供应链中。
坎西安表示,展望未来,预计防空和导弹防御领域的支出将会增加,相关国防企业的业务也会更多。他指出,其中大部分将与特朗普政府的“金顶”计划息息相关。
金穹顶外卡
备受争议的“金穹顶”计划将包括一套庞大的传感器和拦截器——部署在地球、太空以及两者之间的任何地方——根据理论,这将使美国几乎不受任何形式的空中攻击。
关于其确切架构的细节仍然很少,各公司正在寻找进入该项目的途径,他们认为这将是政府数千亿美元支出中足以影响几代人的一笔巨款。
“我们仍然不太清楚它是什么,”坎西安说,并补充说,随着时间的推移,这种缺乏清晰度的情况可能会使整个项目越来越难以推销。
这位分析师表示,总体而言,账面上的国防开支如此之多,以至于美国政府无需在购买传统武器和新技术之间做出选择。
他说:“最让我感到惊讶的是——我是从项目预算的角度来看的——资金竟然足够同时做这两件事。”
如何将大量涌入的国防资金转化为切实有效的国防措施,将是政界人士的首要监督任务。而工业界也必须严于律己,做好充分准备,以应对订单积压和生产瓶颈问题。
正如普华永道分析师斯科特·汤普森在最近对航空航天和国防领域的业绩分析中所指出的那样,“在一个需求不是制约因素的市场中,执行力才是决定性因素。”