Thailand joins minimum tax regime aimed at large global corporations as it integrates into world networks泰国加入针对大型跨国公司的最低税收制度,以融入全球网络
Thailand joins the global tax net with a 15% minimum levy on multinational giants, not expatriates. But overseas account sharing is already live as Bangkok… Read More ›
新闻视频
September 16, 2026 at 11:20 pm
in Economy , Living , Media , Politics , Thailand
Thailand has taken another decisive step into the global tax information system, signing an OECD-backed agreement covering the world’s largest multinationals. The move does not impose a new tax on expatriates. However, it comes as Thailand already exchanges overseas financial account data and tightens taxation of foreign-source income. Meanwhile, officials are preparing wider financial and crypto reporting from 2028. The changes coincide with Thailand’s drive for OECD membership and growing Revenue Department capacity to use information obtained overseas. For foreign residents, the message is significant. GloBE targets multinational giants, but Thailand’s wider cross-border tax network is expanding.
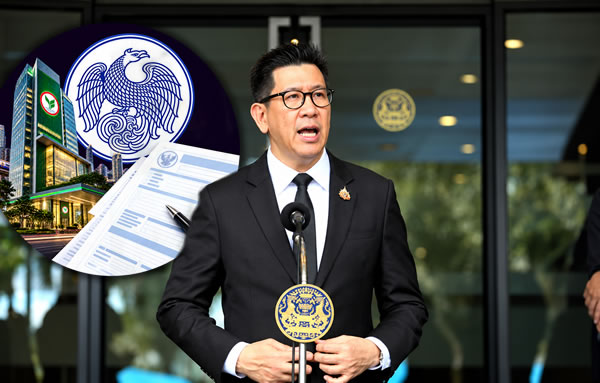
Deputy Prime Minister and Minister of Finance Ekniti Nitithanprapas signs Thailand into the global 15% corporate tax network as overseas account sharing, foreign-income taxation and crypto reporting expand. ( Source: Bangkok Post )
Thailand has taken another major step towards integrating its tax system with the global financial reporting network. However, the latest agreement is not a new tax on expatriates, pensions, foreign remittances or individual residents. Instead, it principally targets some of the world’s largest multinational corporations. Yet its significance extends beyond the companies directly caught by the measure.
Deputy Prime Minister and Finance Minister Ekniti Nitithanprapas announced the move on September 15. Thailand signed the Multilateral Competent Authority Agreement on the Exchange of GloBE Information, known as the GloBE MCAA. The Organisation for Economic Co-operation and Development (OECD) formally listed Thailand as a signatory on September 8. As a result, another section of Thailand’s tax system is joining an international information network.
The immediate measure concerns the Global Minimum Tax and multinational corporations. Separately, Thailand already exchanges financial account information with overseas tax agencies under another international system. It has also tightened the treatment of foreign-source income received by Thai tax residents. Meanwhile, further international reporting arrangements are approaching.
Global minimum tax targets multinational giants while leaving expatriate personal taxation unchanged
For foreign residents, those distinctions are crucial. This month’s GloBE agreement does not expose every expatriate’s overseas bank account to Thailand. Nor does it create a new personal tax liability. Rather, it sits beside other systems which already concern individuals and their financial accounts.
GloBE stands for Global Anti-Base Erosion. It forms the core of Pillar Two of the OECD and G20 international corporate tax reforms. Essentially, the framework establishes a 15% minimum effective tax rate for extremely large multinational groups. It applies across jurisdictions where those groups conduct business.
Where effective taxation falls below 15%, additional tax can potentially become payable. That additional liability is generally known as a top-up tax. Importantly, Thailand did not introduce the Global Minimum Tax this month. The kingdom enacted its Emergency Decree on Top-up Tax B.E. 2567 in December 2024.
The legislation applies to accounting periods beginning from January 1, 2025. Notably, the threshold for entering the regime is exceptionally high. It principally covers multinational groups with consolidated annual revenues of at least €750 million. Generally, that threshold must be reached during two of the preceding four accounting periods.
Accordingly, the regime targets multinational corporate giants. It does not generally concern ordinary Thai companies or small and medium-sized enterprises. Likewise, it has nothing directly to do with an expatriate’s pension or personal overseas bank account. It does not impose tax merely because somebody lives in Thailand.
Thailand joins GloBE information exchange as multinational tax reporting expands across jurisdictions
Ekniti’s latest move instead concerns the exchange of corporate tax information. Thailand has joined the mechanism allowing tax administrations to exchange GloBE Information Returns, known as GIRs. These returns provide information needed to administer the minimum tax across participating jurisdictions.
In practice, the arrangement also streamlines reporting for multinational groups operating across numerous countries. Companies otherwise could face substantially similar information requirements in multiple jurisdictions. Under the framework, relevant information can instead move between participating tax administrations through agreed procedures.
Thailand expects its first GIR exchanges with partner jurisdictions by December 2027. In parallel, the international system itself continues to develop. On September 11, the OECD released another implementation package covering the Global Minimum Tax. The announcement came days after Thailand was formally listed under the exchange agreement.
That package included updated arrangements governing GloBE Information Returns. Additionally, it introduced mechanisms for reviewing national minimum-tax regimes against international rules. Thailand is therefore entering the exchange mechanism as international standardisation and peer review increase.
Thailand protects domestic tax revenue as global 15% minimum reshapes incentives for multinational firms
There was also a direct fiscal reason for Thailand to establish its domestic 15% regime. For decades, Thailand has offered corporate tax incentives to attract large international investors. The Board of Investment has played a central role in that strategy. Corporate tax holidays and reductions have consequently formed an important part of Thailand’s investment offering.
The Global Minimum Tax changes that calculation for multinational groups covered by Pillar Two. For example, a multinational could receive Thai incentives reducing its effective taxation below 15%. Another participating jurisdiction could then potentially collect part of the resulting top-up tax.
Thailand therefore faced the possibility of losing potential revenue to another country. The Revenue Department highlighted that risk when the domestic legislation was introduced. Without its own top-up regime, Thailand could surrender tax that another participating jurisdiction could collect.
In response, Thailand established its domestic mechanism. This allows the kingdom to protect taxation rights connected with qualifying activities conducted inside Thailand. The Global Minimum Tax does not abolish investment incentives. Instead, it changes the value of some corporate tax concessions for the largest multinational groups.
A conventional corporate tax reduction towards zero can become less valuable under Pillar Two. Another jurisdiction may subsequently impose tax, bringing the effective rate towards 15%. Consequently, participating countries must consider how their investment incentives interact with the global minimum.
CRS already gives Thailand access to overseas financial account information under global reporting rules
For expatriates, however, a separate international system carries much greater direct relevance. Thailand has participated in the Common Reporting Standard, or CRS, since 2023. Unlike GloBE, CRS can concern financial accounts connected with individuals.
Thailand activated the CRS Multilateral Competent Authority Agreement and began automatic financial account exchanges in 2023. Therefore, international financial information sharing affecting reportable individual accounts is already operating. It is not a system waiting to be introduced.
Under CRS, financial institutions identify reportable accounts according to international reporting and tax residence rules. They collect prescribed information where an account meets the reporting requirements. Subsequently, that information can reach the relevant domestic tax administration.
Participating tax agencies can then exchange information with partner jurisdictions. As part of this, tax residence plays a central role in determining where information should be reported. A qualifying financial account can therefore generate information beyond the country where the account is maintained.
CRS does not mean every foreign bank account becomes taxable in Thailand. Reporting and taxation remain separate legal questions. Nevertheless, Thailand already possesses formal channels for receiving overseas financial account information where international reporting requirements are satisfied.
Thailand builds tax enforcement capacity as expanded CRS and crypto reporting move closer to launch
The OECD’s 2026 review of tax transparency in Asia provides further details. Thailand successfully began its first CRS exchanges in 2023. More significantly, the country has been developing its ability to use information received through international cooperation.
According to the OECD review, information requests sent by Thailand increased from none to 52. At the same time, more than 400 Thai officials received domestic training. The changes therefore extend beyond installing an electronic reporting mechanism. Thailand is also developing administrative capacity around internationally exchanged tax information.
On another front, CRS itself is expanding. International rules have been amended to cover additional financial products. The changes also seek to improve information available to participating tax administrations. First international exchanges under the amended CRS framework are scheduled for September 2027.
Thailand is preparing changes ahead of participation under the revised framework from 2028. Beyond banking and conventional investments, another reporting system is also approaching. Thailand has committed to implementing the Crypto-Asset Reporting Framework, known as CARF, from 2028.
CARF extends international tax transparency arrangements into reportable crypto-asset transactions. Accordingly, another category of cross-border financial activity will enter a standardised international reporting structure. The framework sits separately from conventional CRS financial account reporting.
Thailand’s tax changes accelerate as foreign-source income rules tighten for residents from 2024
The sequence of Thai changes has accelerated since 2023. First, Thailand began automatic financial account exchanges under CRS. Then, from January 2024, the Revenue Department changed its treatment of relevant foreign-source income.
A year later, Thailand’s Global Minimum Tax became effective. Now, Ekniti has signed the country into the GloBE information exchange mechanism. By December 2027, Thailand expects to exchange multinational GIR information with partner jurisdictions.
From 2028, amended CRS requirements are expected to widen financial reporting further. At that point, Thailand is also preparing to implement CARF. Alongside these measures, the country’s OECD accession process continues.
For individual expatriates, Thai tax residence remains a critical starting point. Generally, somebody spending more than 180 days in Thailand during a calendar year becomes a Thai tax resident. That status can create Thai personal income tax obligations.
Those obligations can cover Thai-source income and relevant foreign-source income brought into Thailand. Crucially, a major change affecting overseas income took effect from January 1, 2024. Previously, the year in which overseas income entered Thailand created an important distinction.
Foreign-source income could generally escape Thai taxation when remitted during a later tax year. Taxpayers could therefore earn overseas income and wait until another year before bringing it into Thailand. That timing treatment changed for relevant foreign income arising from January 1, 2024 onwards.
Foreign income rules preserve key exemptions while tax treaties can reduce liabilities through credits
Under the revised interpretation, delaying a qualifying remittance no longer produces the previous result. Relevant foreign-source income can potentially become taxable when later remitted by a Thai tax resident. Even so, significant limitations remain.
The Revenue Department confirms that foreign-source income earned before January 1, 2024 retains its previous treatment. Thus, subsequently transferring that older money does not bring it under the revised interpretation. The date when income originally arose can therefore be critical.
Tax residence when the income was earned also matters. Income earned while somebody was not a Thai tax resident does not automatically become taxable after a later transfer. Accordingly, source, timing, residence and ownership remain important when determining the Thai position.
Double-taxation agreements add another layer. Thailand’s Revenue Department says the kingdom has agreements with 61 countries. These treaties can allow qualifying foreign taxes already paid to be credited against Thai liabilities.
In addition, the Revenue Department has developed a foreign tax credit calculation system for taxpayers receiving overseas income. The international framework therefore does not automatically tax identical income twice. Instead, liability depends upon Thai law, residence and the nature of the income.
Tax records become more important as Thailand adds a specific declaration for foreign-source income
Applicable double-taxation agreements can then alter the final calculation. Foreign tax already paid may reduce Thai liability where a credit is available. Consequently, documentation becomes increasingly important for residents receiving money from several countries.
Taxpayers may need evidence showing when income arose and where it originated. They may also require documents establishing foreign taxes already paid. Furthermore, residence during the relevant year can determine whether Thailand has a claim on the income.
The date money entered Thailand can remain important as well. Older income may receive different treatment from income arising after January 1, 2024. For that reason, the history behind an overseas transfer can matter as much as the transfer itself.
Another Revenue Department development emerged this month. Its 2026 personal income tax materials specifically include an “Income Declaration for Foreign-Sourced Income”. The relevant Revenue Department webpage was updated on September 10.
This document is separate from Ekniti’s GloBE agreement. Nonetheless, it sits within the same increasingly international tax environment. Thailand is simultaneously dealing with foreign-source income, automatic account information and multinational corporate taxation.
OECD accession brings Thailand under wider scrutiny as 25 committees examine laws and regulations
The OECD accession process provides another part of the background. Thailand formally entered accession discussions with the organisation in June 2024. The OECD adopted Thailand’s accession roadmap the following month.
A further milestone followed in December 2025. Prime Minister Anutin Charnvirakul submitted Thailand’s Initial Memorandum to the OECD. With that step, accession moved into detailed technical examinations.
Twenty-five OECD committees are now examining Thai legislation, regulations and government practices. They are assessing Thailand against relevant OECD standards and instruments. International taxation is therefore one component of a considerably wider regulatory examination.
OECD accession does not itself dictate a particular personal tax regime for expatriates. Thai personal taxation remains governed by domestic legislation and applicable international agreements. Still, tax transparency and international information exchange are already established within Thailand’s current framework.
Three separate international reporting tracks now stand out. The first is GloBE and its GIR information system. It concerns multinational groups exceeding the relevant €750 million revenue threshold.
CRS and CARF widen international reporting while GloBE remains separate from expatriate personal tax
The second is CRS. It concerns automatic financial account information involving reportable individuals and entities. Thailand has participated in that international exchange system since 2023.
The third is CARF. It concerns reportable crypto-asset transactions and is expected to become relevant for Thailand from 2028. Taken separately, the three systems cover different taxpayers, assets and information.
They should therefore not be treated as one tax system. Even so, each expands formal information channels between Thailand and overseas tax administrations. The Revenue Department is becoming connected with a wider range of international financial information.
For an ordinary foreign retiree, this week’s GloBE agreement creates no new personal tax liability. Similarly, a foreign employee acquires no additional personal tax merely because Thailand signed it. A digital worker does not suddenly become taxable because of GloBE either.
Their position instead continues to depend upon existing Thai personal tax rules. Residence is central, while the source of income also matters. The year when foreign income arose can change its treatment.
Remittance timing can remain relevant under the applicable rules. Foreign taxes previously paid may also reduce Thai liability. Finally, an applicable double-taxation agreement can materially change the final calculation.
Wealthier foreign residents face intersecting tax rules as Thailand expands cross-border information flows
For wealthier foreign residents, the broader information network can have greater practical relevance. Such residents may hold bank accounts, investments, brokerage accounts, businesses and property across several jurisdictions. They may also receive dividends, interest, salaries, business profits or rental income overseas.
Where those residents fall within Thai taxation, several systems can intersect. Domestic law determines whether a Thai liability arises. Double-taxation agreements can affect how much is payable. CRS can separately provide reportable financial account information to participating tax administrations.
Beginning in 2028, CARF is expected to add another reporting channel for qualifying crypto assets. GloBE, meanwhile, will perform a different function for large multinational groups. Each system therefore has its own legal purpose and reporting population.
Thailand’s own 2026 guidance already addresses foreign-source income and foreign tax credits. At the same time, its international reporting commitments continue expanding. The changes have accumulated quickly.
In 2023, Thailand entered automatic CRS financial account exchanges. From January 2024, it tightened treatment of relevant foreign-source income. Its domestic Global Minimum Tax then became effective from January 2025.
This month brings Ekniti’s GloBE information exchange agreement. By December 2027, Thailand expects its first multinational GIR exchanges with partner jurisdictions. From 2028, revised CRS requirements and crypto-asset reporting are expected to widen the network again.
Thailand’s international tax network expands as OECD scrutiny and new reporting systems gather pace
Meanwhile, 25 OECD committees continue examining Thailand during its membership accession process. Against that background, this week’s signing is not an isolated technical agreement. It adds another international channel to a tax infrastructure already undergoing rapid change.
The immediate target remains multinational corporations and an effective corporate tax rate of at least 15%. For expatriates, CRS and Thailand’s foreign-source income rules remain the more directly relevant systems.
Yet Thailand’s wider international tax integration is already well advanced. Financial account exchanges have operated since 2023. Foreign-source income reporting has become more prominent, while crypto-asset reporting is approaching.
Thailand is also training hundreds of officials in international tax transparency. Its requests for overseas tax information have increased from none to 52. Moreover, international agreements now provide standardised channels for information to move between tax administrations.
Ekniti’s September signing adds the multinational corporate side to that expanding structure. Large groups will face internationally coordinated minimum-tax information reporting. Individual foreign residents remain governed by separate personal tax, treaty and CRS rules.
The systems are different, but Thailand’s tax infrastructure increasingly reaches across national borders. This month’s GloBE agreement takes that process another significant step forward.
Thailand’s stiff restrictions on small foreign investors a significant problem for its daring OECD aspirations
Economy to be transformed with new reverse income tax system. Everyone in Thailand will report income
Prachachart Party leader warns public finances face a deep crisis with falling tax income and more debt
Tax and welfare revolution as Thailand moves ahead with Negative Income Tax that expands reporting
Thumbs up from economic gurus for 2027 Negative Income Tax plan. It’s a game-changer for progress
Huge economic change as Reverse Tax plan is being pushed by the Pheu Thai government as it battles on
Expert warns foreign tourism has become Thailand’s curse, fueling inertia and a widespread malaise
No more surprises or shocks. Thai foreign tourism players warn of a bad year with arrivals down 6.56%
Tourism chief rebuts distorted scam centre reports linked to Taiwanese tourists. Now, a new, safer order
Tourism chief targets European tourists in the second half of 2025 while cabinet orders shorter visas
Thai economy thrown into disarray by Trump’s tariffs. Exports and Tourism may both be far lower in 2025
Pichai’s team not to fly to the United States this week but next week as US-Chinese tensions escalate
Joseph Anthony is an expat from Ireland who has lived in Thailand for the last decade. He has worked extensively in the media including editorial positions in Ireland and Thailand. He is focused on economic and business stories in Thailand as well as the expat lifestyle.
All posts by Joseph O' Connor
TH AI plan runs into problems and bottlenecks. New AIS deal offering cheap 29 baht per month internet September 13, 2026 Thailand’s flagship ฿1.6 billion AI scheme hits
Prime Minister scrambles to get data centre sector back on track after energy and regulatory hiatus September 13, 2026 Thailand’s data centre boom hits a regulatory wall
Mystery Chinese man used lost phone to lure Thai woman into trap at his condo and sexually attack her September 12, 2026 Pattaya woman Beam Mukassara claims a Chinese man
Former Ayutthaya abbot and his mistress sent to jail as court denies them bail as police probe finances September 12, 2026 Sex, cash and gold engulf a royal Ayutthaya temple as
Rising concerns in tourist hotspots about unruly tourists from Middle Eastern countries refusing to pay September 12, 2026 Foreign tourist mocks a Phuket motorcycle rider and
American wanted for sex offences against female minors arrested at Chiang Mai Buddhist retreat September 11, 2026 Thai police infiltrate a Chiang Mai meditation retreat
PM Anutin’s mission to Oslo to represent Thailand at the funeral of King Harald V amid budget scrutiny by the opposition September 11, 2026 Royal mission puts Anutin among monarchs and world
Bank of Thailand warns economic potential is falling with a severe crisis in the small business sector September 11, 2026 Thailand faces a widening economic split as exports
Masked man stages armed robbery in Pathum Thani netting 1.5 million baht before torching getaway car September 10, 2026 Gunman seals six people inside a Talat Thai bank,
Police officer bursts into tears as he surrenders to police led by son a day after murdering his wife September 10, 2026 Kindergarten killing ends in a dramatic dawn surrender
Court denies mercy to savage killer who bludgeoned a hotel worker to death in a drug crazed robbery in Hua Hin September 9, 2026 Death for Hua Hin hotel killer Rattikorn “Sam”
Summonses and criminal charges considered by DSI in probe into substantial Israeli network in Pattaya September 9, 2026 Israeli businessman Maimon David Marsiano faces a DSI
Dutch man entered into a mediated settlement after assaulting a young Thai woman at a Koh Samui bar September 9, 2026 CCTV catches a Dutch man repeatedly striking a Thai
French man held at Koh Samui Police Station as deportation process begins. Israeli moved to Bo Phut September 9, 2026 Kevin Dimino is behind bars on Koh Samui after PM
Local government exam scandal hints at systemic nationwide corruption even extending to ministerial level September 8, 2026 Pakamon blows open a new front in Thailand’s exam
Government begins legal action against top Thai firms for 1.26 billion baht over key satellite concession September 8, 2026 Thailand races to pursue Thaicom and Gulf for
Indian tourist severely injured but coherent after early morning fall last Friday from his Pattaya hotel September 8, 2026 Indian tourist Abhishek Jagannath Kunjir, 42, suffers
Sex and financial scandal at famous monastery rocks Thailand. Abbot and girlfriend amassed huge wealth September 13, 2026
Thailand hailed as a haven for retirees and digital nomads but officials breed doubt and uncertainty September 12, 2026
Commerce Minister Suphajee responds to Sondhi Limthongkul’s attack on new liberal investment rules September 12, 2026
Pressure movement against Israel in Thailand gains momentum as it combines with street protests September 12, 2026
Bank bandit arrested at a Bangkok resort. 54 year old Saifa Kasemut has a history of armed robbery crime September 12, 2026
Former Prime Minister and Democrat Party leader cites a lack of public trust in the Election Commission September 11, 2026
Foreign nominee companies down by 81.77% as government seizes or freezes assets of over 20 billion September 11, 2026
Ayutthaya abbot disrobes as top temple official is arrested by police who worked undercover for months September 10, 2026
Veteran protest leader and media boss Sondhi begins his street protest campaign at Israel’s Embassy September 10, 2026
Substantial US Thai trade deal ready to be finalised by a call between Anutin and Trump says Minister September 10, 2026
Pattaya police officer clinically executed his wife at a kindergarten and was later surrounded at home September 9, 2026
Thailand gets ready to enter the age of nuclear power with plans for two small modular reactors by 2037 September 9, 2026
Petrol and diesel rise as inflation for August comes in at 2.53%. However confidence is also seen rising September 9, 2026
Nationwide probe targeting over 36K foreigner linked firms with land and a further 7k which own condos September 8, 2026
Sex network boss arrested in shock police home raid on Sunday after probe exposed child porn racket September 8, 2026
Activist lawyer wants action on corruption which pilfers lottery revenue for the disabled for the rich September 8, 2026
Interior Ministry is now moving to enforce the law regarding Jewish burials and grave sites in Thailand September 7, 2026
Chaos still reigns at the NBTC as Chairman wins right to court review. Board members move to work on September 7, 2026
Vicious attack on UK man in Jomtien Pattaya leads to arrest of Thai man. 70 year old kicked in the face September 7, 2026
USS Abraham Lincoln departs Thailand after a special visit. Captain gave thanks for the very warm welcome September 6, 2026
Tourism sector starkly divided over 30 days visa from September 15th. Top tycoon says it’s a big mistake September 6, 2026
Missing Kanchanaburi mother found on southbound bus after 7 day northern stay shrouded in mystery September 6, 2026
© 2026 Thai Examiner. All rights reserved.
2026年9月16日晚上11点20分
经济、生活、媒体、政治、泰国
泰国在融入全球税务信息体系方面又迈出了重要一步,签署了一项由经合组织支持的协议,该协议涵盖了全球最大的跨国公司。此举不会对在泰外籍人士征收新税。然而,与此同时,泰国已在交换海外金融账户数据,并加强了对境外收入的征税。此外,泰国官员正准备从2028年起扩大金融和加密货币信息报告的范围。这些变化与泰国加入经合组织的进程以及税务部门不断提升利用海外信息的能力相契合。对于外国居民而言,这意义重大。GloBE协议的目标群体是跨国巨头,但泰国更广泛的跨境税务网络正在不断扩展。
随着海外账户共享、境外收入征税和加密货币申报等问题的日益增多,泰国副总理兼财政部长埃克尼提·尼提坦帕帕斯签署协议,泰国加入全球15%企业所得税网络。(来源:曼谷邮报)
泰国在将税收体系与全球财务报告网络(GFRN)整合方面又迈出了重要一步。然而,最新协议并非针对外籍人士、养老金、海外汇款或个人居民征收新税,而是主要针对一些全球最大的跨国公司。但其意义远不止于直接受该措施影响的公司。
泰国副总理兼财政部长埃克尼提·尼提坦帕帕斯于9月15日宣布了这一举措。泰国签署了《关于交换全球信息(GloBE)的多边主管当局协议》(简称GloBE MCAA)。经济合作与发展组织(OECD)于9月8日正式将泰国列入该协议的签署国名单。由此,泰国税收系统又新增了一个部分,加入了国际信息网络。
当前措施涉及全球最低税和跨国公司。此外,泰国已根据另一项国际体系与海外税务机构交换金融账户信息,并收紧了对泰国税务居民所获境外收入的监管。与此同时,更多国际报告安排也即将出台。
全球最低税目标针对跨国巨头,同时维持外籍人士个人所得税不变。
对于外国居民而言,这些区别至关重要。本月的GloBE协议并非将所有外籍人士的海外银行账户都暴露给泰国,也不会产生新的个人纳税义务。相反,它与其他已涉及个人及其金融账户的系统并存。
GloBE 代表全球反税基侵蚀机制,是经合组织和二十国集团国际企业税制改革第二支柱的核心内容。该框架实质上为超大型跨国集团设定了 15% 的最低有效税率,并适用于这些集团开展业务的所有司法管辖区。
当实际税率低于15%时,可能需要缴纳额外税款。这种额外税负通常被称为补充税。值得注意的是,泰国本月并未实施全球最低税。泰国于2024年12月颁布了《补充税紧急法令》(佛历2567年)。
该法规适用于2025年1月1日之后开始的会计期间。值得注意的是,适用该法规的门槛极高。它主要针对合并年收入至少达到7.5亿欧元的跨国集团。通常情况下,该门槛必须在之前的四个会计期间中的两个期间达到。
因此,该制度针对的是跨国公司巨头,一般不涉及普通的泰国公司或中小企业。同样,它也与外籍人士的养老金或个人海外银行账户没有直接关系。该制度不会仅仅因为某人居住在泰国就征税。
随着跨国税务报告范围扩大至多个司法管辖区,泰国加入GloBE信息交换平台
Ekniti 的最新举措则涉及企业税务信息的交换。泰国已加入允许税务机关交换全球税务信息申报表(简称 GIR)的机制。这些申报表提供参与国之间征收最低税所需的必要信息。
实际上,该安排也简化了跨国集团在多个国家开展业务的报告流程。否则,公司可能在多个司法管辖区面临实质上相同的信息要求。根据该框架,相关信息可以通过约定的程序在参与的税务机关之间转移。
泰国预计将于2027年12月前与伙伴司法管辖区首次进行全球最低税(GIR)交换。与此同时,国际体系本身也在不断发展。9月11日,经合组织发布了另一套涵盖全球最低税的实施方案。此前几天,泰国刚刚被正式列入交换协议名单。
该方案包括更新后的环球信息申报安排。此外,它还引入了根据国际规则审查国家最低税制的机制。因此,随着国际标准化和同行评审的加强,泰国正在加入这一信息交换机制。
泰国保护国内税收,因为全球15%的最低税率重塑了跨国公司的激励机制。
泰国设立15%的国内税率制度还有直接的财政原因。几十年来,泰国一直提供企业税收优惠政策以吸引大型国际投资者。泰国投资促进委员会在这一战略中发挥了核心作用。因此,企业税收假期和减免政策已成为泰国吸引投资的重要组成部分。
全球最低税改变了第二支柱涵盖的跨国集团的税率计算方式。例如,一家跨国公司可能获得泰国政府的优惠政策,使其实际税率降至15%以下。其他参与国则有可能征收由此产生的部分额外税款。
因此,泰国面临着将潜在税收收入拱手让给其他国家的风险。税务部门在制定国内立法时就强调了这一风险。如果没有自己的税收补充机制,泰国可能会放弃其他参与国可以征收的税款。
为此,泰国建立了国内机制。该机制使泰国能够保护与在泰国境内开展的符合条件的活动相关的税收权利。全球最低税并未取消投资激励措施,而是改变了部分大型跨国集团可享受的企业税收优惠的价值。
在第二支柱下,传统的企业所得税减免至零的价值可能会降低。其他司法管辖区随后可能会征税,使实际税率接近15%。因此,参与国必须考虑其投资激励措施如何与全球最低税率相互作用。
根据全球报告规则,CRS已经允许泰国获取海外金融账户信息。
然而,对于外籍人士而言,另一套国际体系则具有更为直接的相关性。泰国自2023年起参与了共同申报准则(CRS)。与全球财务报告准则(GloBE)不同,CRS可以涵盖与个人相关的金融账户。
泰国已于2023年启动了CRS多边主管当局协议,并开始自动交换金融账户信息。因此,影响应申报个人账户的国际金融信息共享机制已投入运行,并非待引入的系统。
根据CRS,金融机构根据国际报告和税务居民身份规则识别应报告账户。如果账户符合报告要求,金融机构会收集规定的信息。随后,这些信息可以送达相关的国内税务机关。
参与的税务机构可以与合作司法管辖区交换信息。在此过程中,税务居民身份在确定信息申报地点方面起着核心作用。因此,符合条件的金融账户可以产生账户所在国以外的信息。
CRS并不意味着所有境外银行账户在泰国都需要缴税。申报和征税仍然是两个独立的法律问题。尽管如此,泰国已经拥有正式渠道接收符合国际申报要求的境外金融账户信息。
随着CRS扩展和加密货币报告机制的推出日益临近,泰国加强了税务执法能力。
经合组织2026年对亚洲税务透明度的评估报告提供了更多细节。泰国于2023年成功启动了首批CRS信息交换。更重要的是,泰国一直在提升其利用国际合作所获信息的能力。
根据经合组织的评估,泰国发送的信息请求数量从零增加到52份。与此同时,超过400名泰国官员接受了国内培训。因此,这些变化不仅限于建立电子报告机制。泰国还在加强与国际税务信息交换相关的行政能力建设。
另一方面,CRS本身也在不断扩展。国际规则已进行修订,以涵盖更多金融产品。这些修订还旨在改善参与税务机关可获取的信息。根据修订后的CRS框架进行的首次国际信息交换计划于2027年9月进行。
泰国正为参与2028年修订后的框架做准备。除了银行和传统投资之外,另一套报告系统也即将实施。泰国已承诺从2028年起实施加密资产报告框架(CARF)。
CARF将国际税务透明度安排扩展至可报告的加密资产交易。因此,又一类跨境金融活动将纳入标准化的国际报告体系。该框架独立于传统的CRS金融账户报告。
泰国税收改革加速推进,自2024年起,居民的境外收入规定将更加严格。
自2023年以来,泰国的一系列改革措施加速推进。首先,泰国开始根据共同申报准则(CRS)自动交换金融账户信息。随后,自2024年1月起,泰国税务局改变了对相关境外收入的处理方式。
一年后,泰国的全球最低税正式生效。如今,泰国已加入Ekniti的全球最低税信息交换机制(GloBE)。泰国预计将于2027年12月前与合作司法管辖区交换多国全球最低税信息。
自2028年起,修订后的CRS要求预计将进一步扩大财务报告的范围。届时,泰国也将准备实施CARF准则。与此同时,泰国的经合组织入盟进程也在继续推进。
对于个人外籍人士而言,泰国税务居民身份仍然是一个至关重要的起点。通常情况下,在一年内于泰国停留超过180天的人即成为泰国税务居民。这种身份可能导致其承担泰国个人所得税的义务。
这些义务涵盖源自泰国的收入以及汇入泰国的相关境外收入。至关重要的是,一项影响境外收入的重大变更已于2024年1月1日生效。此前,境外收入进入泰国的年份是区分其归属的重要依据。
通常情况下,境外收入如果在后续纳税年度汇回泰国,可以免缴泰国税款。因此,纳税人可以在海外赚取收入,然后等到下一个纳税年度再将其汇入泰国。但自2024年1月1日起,相关境外收入的汇款时间规定发生了变化。
外国收入规则保留了关键的豁免条款,而税收协定可以通过税收抵免来减少纳税义务。
根据修订后的解释,延迟汇款不再产生之前的结果。相关的境外收入在泰国税务居民之后汇出时,可能需要纳税。即便如此,仍然存在诸多限制。
税务部门确认,2024年1月1日之前获得的境外收入仍按原规定处理。因此,之后转移这笔较早获得的资金并不适用修订后的解释。收入最初产生的日期至关重要。
收入的税务居民身份(即收入产生时的税务居民身份)也很重要。某人在非泰国税务居民期间获得的收入,在之后转移给其他人后,并不会自动变成泰国税务居民。因此,在确定其泰国税务身份时,收入来源、时间、居住地和所有权等因素仍然至关重要。
双重征税协定又增加了一层复杂性。泰国税务局表示,泰国已与61个国家签订了此类协定。这些协定允许已缴纳的符合条件的外国税款抵免泰国的应纳税额。
此外,税务部门已为收取海外收入的纳税人制定了外国税收抵免计算系统。因此,国际框架不会对同一笔收入自动征税两次。相反,纳税义务取决于泰国法律、纳税人居住地以及收入性质。
随着泰国新增针对境外收入的特定申报要求,税务记录的重要性日益凸显。
适用的避免双重征税协定可能会影响最终的计算结果。已缴纳的外国税款在可获得抵免的情况下,可能会减少泰国的应纳税额。因此,对于从多个国家收取款项的居民来说,文件准备工作变得越来越重要。
纳税人可能需要提供证据,证明收入产生的时间和来源地。他们也可能需要提供文件,证明已缴纳的外国税款。此外,纳税人在相关年度的居住地也会影响泰国是否对该收入拥有征税权。
资金进入泰国的日期也至关重要。较早的收入可能与2024年1月1日之后产生的收入适用不同的税务处理方式。因此,海外汇款的历史记录与汇款本身同样重要。
本月税务局又出台了一项新规定。其2026年个人所得税相关文件中特别新增了“境外所得收入申报表”。税务局相关网页已于9月10日更新。
这份文件与Ekniti的GloBE协议是相互独立的。然而,它同样处于日益国际化的税务环境中。泰国同时面临着境外收入、自动账户信息披露和跨国公司税收等问题。
加入经合组织后,泰国将受到更广泛的审查,25个委员会将审查其法律法规。
经合组织入盟进程提供了另一部分背景信息。泰国于2024年6月正式启动与该组织的入盟谈判。经合组织于次月通过了泰国的入盟路线图。
2025年12月,又一个里程碑事件发生。泰国总理阿努廷·查恩维拉库尔向经合组织提交了泰国的初步备忘录。至此,加入经合组织的进程进入了详细的技术审查阶段。
目前,经合组织25个委员会正在审查泰国的立法、法规和政府实践。他们正根据经合组织的相关标准和工具对泰国进行评估。因此,国际税收只是这项更为广泛的监管审查的一个组成部分。
加入经合组织本身并不规定针对外籍人士的特定个人所得税制度。泰国的个人所得税仍然受国内立法和适用的国际协议约束。不过,泰国现行框架内已建立了税收透明度和国际信息交流机制。
目前主要有三条独立的国际报告途径。第一条是GloBE及其GIR信息系统,它适用于营业额超过7.5亿欧元门槛的跨国集团。
CRS 和 CARF 扩大了国际报告范围,而 GloBE 则与外籍人士个人所得税无关。
第二项是CRS。它涉及应申报个人和实体的自动财务账户信息。泰国自2023年起参与该国际信息交换体系。
第三个系统是CARF。它涉及可报告的加密资产交易,预计将从2028年起对泰国生效。单独来看,这三个系统涵盖不同的纳税人、资产和信息。
因此,不应将它们视为同一税收体系。即便如此,它们各自都拓展了泰国与海外税务机关之间的正式信息渠道。泰国税务部门正与更广泛的国际金融信息建立联系。
对于普通的外国退休人员而言,本周签署的GloBE协议不会产生新的个人所得税负担。同样,外国雇员也不会仅仅因为泰国签署了该协议就增加个人所得税。数字工作者也不会因为GloBE协议而突然需要纳税。
他们的税务地位仍然取决于现行的泰国个人所得税法。居住地是关键因素,收入来源也至关重要。境外收入产生的年份可能会影响其税务处理方式。
根据适用规则,汇款时间仍然可能具有重要意义。先前已缴纳的外国税款也可能减少泰国的纳税义务。最后,适用的双重征税协定可能会对最终计算结果产生重大影响。
随着泰国扩大跨境信息流动,富裕的外国居民面临着相互交织的税收规则。
对于较富裕的外国居民而言,更广泛的信息网络具有更大的实际意义。这类居民可能在多个司法管辖区拥有银行账户、投资、证券账户、企业和房产。他们也可能在海外获得股息、利息、薪金、商业利润或租金收入。
如果这些居民属于泰国纳税范围,则可能涉及多个系统。泰国国内法决定是否存在泰国纳税义务。双重征税协定会影响应缴税额。CRS 可以单独向参与的税务机关提供可报告的财务账户信息。
预计从2028年开始,CARF将新增一个合格加密资产的报告渠道。与此同时,GloBE将为大型跨国集团提供不同的服务。因此,每个系统都有其自身的法律目的和报告对象。
泰国2026年发布的指导意见已经涉及境外收入和境外税收抵免。与此同时,其国际报告义务也在不断扩大。这些变化累积起来非常迅速。
2023年,泰国开始自动进行CRS金融账户交换。自2024年1月起,泰国收紧了对相关境外收入的税务处理。其国内全球最低税则于2025年1月生效。
本月,Ekniti与GloBE签署了信息交换协议。预计到2027年12月,泰国将与合作司法管辖区建立首个跨国GIR信息交换网络。从2028年起,修订后的CRS要求和加密资产报告预计将进一步扩大该网络。
随着经合组织审查力度加大和新的报告制度加快推进,泰国的国际税务网络也在不断扩大。
与此同时,经合组织25个委员会仍在继续审查泰国加入经合组织的进程。在此背景下,本周签署的协议并非一项孤立的技术性协议,而是为本已快速变革的泰国税收体系增添了又一条国际渠道。
眼下的目标仍然是跨国公司,以及至少15%的有效企业所得税率。对于外籍人士而言,CRS和泰国的境外收入规则仍然是更直接相关的体系。
然而,泰国更广泛的国际税收一体化进程已经取得了长足进展。金融账户交换自2023年起已开始运作。境外收入申报制度日益突出,而加密资产申报制度也即将实施。
泰国还在培训数百名官员,提升其国际税务透明度。其向海外税务机关索取信息的请求数量已从零增加到52份。此外,国际协议也为税务机关之间的信息流动提供了标准化的渠道。
Ekniti 9 月份的签署将跨国公司纳入了这一不断扩展的框架。大型集团将面临国际协调的最低税务信息申报要求。外国居民个人仍受单独的个人所得税、税收协定和共同申报准则 (CRS) 的约束。
尽管各国的制度有所不同,但泰国的税收基础设施正日益跨越国界。本月签署的GloBE协议标志着这一进程又向前迈出了重要一步。
泰国对小型外国投资者的严格限制对其雄心勃勃的经合组织入盟目标构成重大障碍。
新的反向所得税制度将彻底改变泰国经济。泰国所有居民都需申报收入。
普拉查特党领导人警告称,由于税收收入下降和债务增加,公共财政面临严重危机。
泰国推进负所得税政策,扩大申报范围,税收和福利制度迎来革命性变革。
经济专家们对2027年负所得税计划表示赞赏。这将是推动经济进步的变革性举措。
为泰政府正力推逆向税收计划,这将带来巨大的经济变革,因为该政府正在与……作斗争。
专家警告:外国游客已成为泰国的祸根,加剧了经济停滞和普遍的萎靡不振。
一切如常,毫无意外。泰国外国旅游业人士警告称,今年将是糟糕的一年,入境游客人数下降了6.56%。
旅游局局长驳斥了有关台湾游客的歪曲报道,称诈骗中心正在实施新的、更安全的秩序。
旅游局长计划在2025年下半年吸引更多欧洲游客,同时内阁下令缩短签证期限。
特朗普的关税政策使泰国经济陷入混乱。到2025年,出口和旅游业可能都会大幅下滑。
由于中美紧张局势升级,皮查伊的团队本周不会飞往美国,而是下周前往。
约瑟夫·安东尼是一位来自爱尔兰的侨民,过去十年一直居住在泰国。他曾在爱尔兰和泰国的媒体行业担任过编辑职务,拥有丰富的媒体从业经验。他主要关注泰国的经济和商业新闻,以及侨民的生活方式。
约瑟夫·奥康纳的所有帖子
泰国人工智能计划遭遇困境和瓶颈。新的AIS协议提供每月29泰铢的低价互联网服务,预计于2026年9月13日生效。泰国耗资16亿泰铢的旗舰人工智能计划遭遇挫折。
泰国总理紧急采取措施,力图在能源和监管停滞后重振数据中心行业(2026年9月13日) 泰国数据中心热潮遭遇监管壁垒
2026年9月12日,芭堤雅女子Beam Mukassara称,一名神秘中国男子利用丢失的手机将一名泰国女子诱骗至其公寓并对其进行性侵。
前阿瑜陀耶寺住持及其情妇因涉嫌财务纠纷被法院拒绝保释并送入监狱(2026年9月12日) 性、现金和黄金充斥着阿瑜陀耶皇家寺庙
旅游热点地区日益关注来自中东国家的游客拒付车费等不文明行为。2026年9月12日,一名外国游客在普吉岛嘲笑一名摩托车骑手。
2026年9月11日,一名因性侵未成年女性而被通缉的美国男子在清迈佛教静修中心被捕。泰国警方渗透了清迈的一处冥想静修中心。
2026年9月11日,在反对党对预算进行审查之际,阿努廷总理将代表泰国前往奥斯陆参加哈拉尔五世国王的葬礼。此次皇家访问使阿努廷与君主和世界各国领导人齐聚一堂。
泰国央行警告称,小企业部门面临严重危机,经济潜力正在下降(2026年9月11日) 随着出口下滑,泰国面临日益扩大的经济分化
2026年9月10日,一名蒙面男子在巴吞他尼实施武装抢劫,劫走150万泰铢后焚毁了逃跑车辆。同日,一名持枪男子将六人困在一家泰泰银行内。
2026年9月10日,一名警官在儿子带领下向警方投降,他痛哭流涕,此前一天他刚刚杀害了自己的妻子。幼儿园枪击案以黎明时分的戏剧性投降告终。
2026年9月9日,华欣一名酒店凶手拉提科恩·“萨姆”·阿特金斯被判死刑,此前他因吸毒后神志不清而抢劫并残忍地将一名酒店员工殴打致死。
2026年9月9日,泰国特别调查局(DSI)考虑对芭堤雅一个庞大的以色列人网络展开调查,并考虑发出传票和提出刑事指控。以色列商人迈蒙·大卫·马尔西亚诺(Maimon David Marsiano)面临泰国特别调查局的调查。
2026年9月9日,一名荷兰男子在苏梅岛一家酒吧殴打一名年轻的泰国女子后,经调解达成和解。监控录像显示,该荷兰男子多次殴打一名泰国女子。
一名法国男子被关押在苏梅岛警察局,遣返程序即将开始。一名以色列男子于2026年9月9日被转移到波普特。凯文·迪米诺在首相下台后被关押在苏梅岛。
地方政府考试丑闻暗示全国范围内存在系统性腐败,甚至蔓延至部长级层面 2026年9月8日 帕卡蒙揭露泰国考试丑闻新篇章
泰国政府于2026年9月8日对泰国主要公司提起诉讼,追讨12.6亿泰铢的卫星特许经营权欠款。泰国正加紧追究Thaicom和Gulf公司的责任。
2026年9月8日,上周五清晨,一名印度游客从芭堤雅的酒店坠落,身受重伤但意识清醒。这名印度游客名叫阿比舍克·贾甘纳特·昆吉尔,42岁。
泰国著名寺院爆出性丑闻和财务丑闻。住持及其女友聚敛巨额财富。2026年9月13日
泰国被誉为退休人士和数字游民的天堂,但官员们却散布疑虑和不确定性 2026年9月12日
商务部长苏帕吉回应桑迪·林通库对新自由投资规则的抨击 2026年9月12日
泰国针对以色列的施压运动与街头抗议活动相结合,势头强劲 2026年9月12日
曼谷一家度假村逮捕了一名银行劫匪。54岁的赛法·卡塞穆特曾有持械抢劫前科。2026年9月12日
前总理兼民主党领袖指出公众对选举委员会缺乏信任 2026年9月11日
2026年9月11日,由于政府查封或冻结超过200亿美元的资产,外国代理公司数量下降了81.77%。
阿瑜陀耶寺住持脱去僧袍,此前警方秘密潜伏数月后逮捕了寺庙高级官员 2026年9月10日
资深抗议领袖兼媒体大佬桑迪于2026年9月10日在以色列大使馆前发起街头抗议活动。
泰国部长阿努廷表示,美泰实质性贸易协议有望在阿努廷与特朗普通话后最终敲定(2026年9月10日)
2026年9月9日,芭堤雅一名警察在幼儿园枪杀了妻子,随后在家中被警方包围。
泰国准备进入核电时代,计划在2037年前建成两座小型模块化反应堆(2026年9月9日)
受8月份通胀率2.53%的影响,汽油和柴油价格上涨。然而,市场信心预计在2026年9月9日也会上升。
全国范围内的调查目标是超过3.6万家与外国人有关联的土地公司和另外7000家拥有公寓的公司 2026年9月8日
2026年9月8日,一名性交易网络头目因涉嫌儿童色情犯罪活动于周日被警方突袭逮捕。
维权律师呼吁对挪用残疾人彩票收入、为富人谋利的腐败行为采取行动 2026年9月8日
泰国内政部将于2026年9月7日开始执行有关犹太人葬礼和墓地的法律。
国家广播电视和电信委员会(NBTC)内部依然混乱,主席赢得诉诸法庭的权利。委员会成员将于2026年9月7日开始工作。
一名英国男子在芭堤雅中天区遭到恶性袭击,一名泰国男子被捕。一名70岁老人于2026年9月7日被踢中面部。
“亚伯拉罕·林肯”号航空母舰结束对泰国的特别访问后离开。舰长对泰国的热情接待表示感谢。2026年9月6日
旅游业对9月15日起实施的30天签证政策存在严重分歧。一位顶级大亨称此举是一个巨大的错误。(2026年9月6日)
2026年9月6日,一名失踪的北碧府母亲在北部逗留7天后,在一辆南行巴士上被发现,失踪原因至今成谜。
© 2026 Thai Examiner。版权所有。