Despite stock slide, reason remains for optimism in Sheng Siong business outlook: Analysts尽管股价下跌,但分析师仍认为昇菘超市的业务前景保持乐观。
Sheng Siong’s share price tumbled 15 per cent over three trading sessions after it flagged a competitive grocery retail landscape in its third-quarter results.
Sheng Siong’s share price tumbled 15 per cent over three trading sessions after it flagged a competitive grocery retail landscape in its third-quarter results.
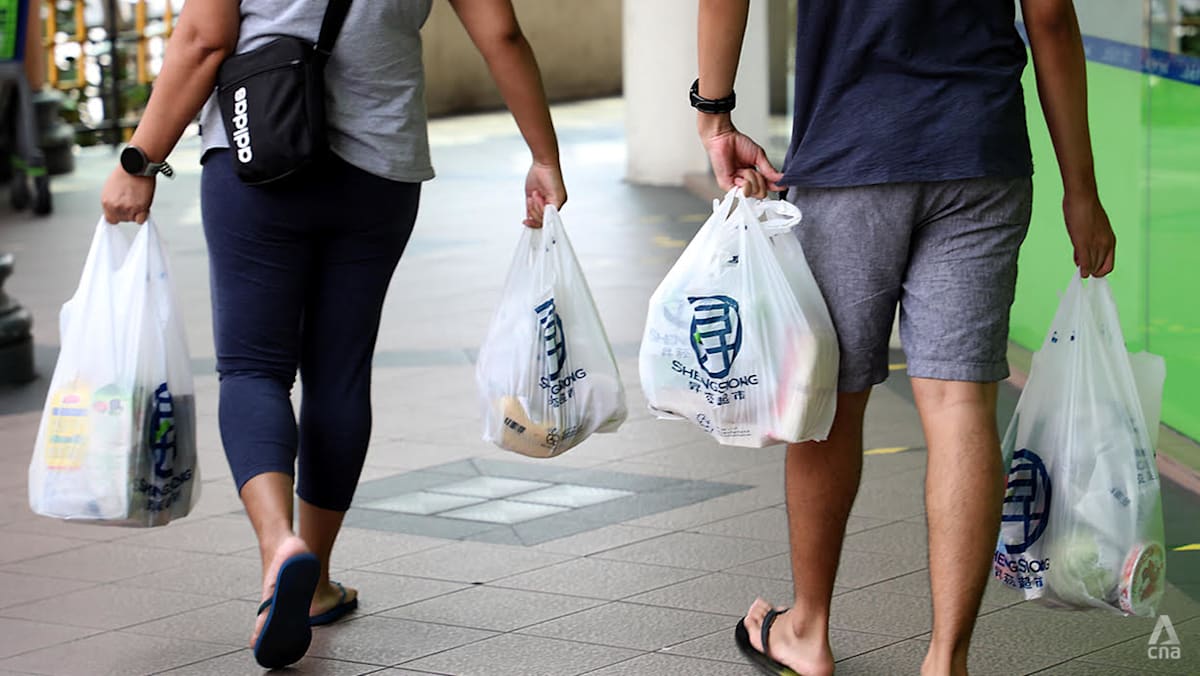
Shoppers leaving a Sheng Siong supermarket with their buys. (Photo: TODAY file)
This audio is generated by an AI tool.
SINGAPORE: Despite Sheng Siong’s share price tumbling 15 per cent over three trading sessions, some analysts remain optimistic about the supermarket operator’s outlook.
“Structurally, Sheng Siong is gaining market share in the grocery sector especially in fresh food sales,” Mr Paul Chew, head of research at Phillip Securities Research, told CNA on Tuesday (Nov 3).
Sheng Siong opened three stores in the third quarter ending Sep 30, raising the group's number of new stores for the year to seven. The group now operates a total of 92 stores in Singapore.
In Mr Chew's view, new store openings are the core driver of the company’s growth and share gains, and competition has retreated over the past two to three years.
CGS International Securities, too, likes Sheng Siong for its earnings growth, which is backed by new store expansion and strong operational execution, said analyst Meghana Kande.
CGS International Securities has maintained its “add” call on Sheng Siong, while Phillip Securities has a “hold” position.
RHB Singapore’s senior research analyst Alfie Yeo has a “buy” call on the stock.
“We believe that (Sheng Siong Group’s) share price can continue to increase if its earnings growth persists,” said Mr Yeo.
WELL-POSITIONED DESPITE GLOOMY OUTLOOK
The decline in Sheng Siong’s share price began on Friday after the company reported its third-quarter results, flagging a competitive grocery retail landscape and sustained promotions that pressure revenue and margins.
The management also highlighted rising costs due to wage increases and higher diesel prices, and the upcoming impact of the Johor Bahru-Singapore Rapid Transit System Link (RTS), that could intensify price competition.
However, it added that the company is well-placed to weather geopolitical uncertainties and disruptions as well as potential competition from the RTS Link, as "consumers are expected to remain value-conscious amid elevated living costs".
Net profit increased 1.8 per cent from a year ago.
The stock closed 4.6 per cent lower on Friday, followed by 9.4 per cent on Monday.
On Tuesday, the stock dipped another 2.5 per cent lower, closing the day at its lowest in a year.
OCBC equity analyst Chu Peng said the sell-off appears to be driven by a softer outlook for next year, rather than the results for the third quarter.
“Investors are pricing in the risk of slower store expansion, higher electricity and labour costs, and the resulting pressure on margins,” she said.
CNA Games Guess Word Crack the word, one row at a time Buzzword Create words using the given letters Mini Sudoku Tiny puzzle, mighty brain teaser Mini Crossword Small grid, big challenge Word Search Spot as many words as you can Show More Show Less
Ms Chu added that the stock was trading at a price-to-earnings ratio that was more than two standard deviations above its historical average, “leaving little room for disappointment and making the stock more vulnerable to a sharper correction amid slower growth and rising cost risk”.
CGS International Securities’ Ms Kande said the stock has had a decent rally this year, and investors may be taking some money off the table.
Asked about SG60 vouchers, which Sheng Siong said gave revenue and sales a boost in the third quarter of last year, Ms Kande downplayed their impact, describing vouchers as an "ad-hoc bonus".
Even as vouchers taper off, Sheng Siong’s fundamental positioning as a value-for-money supermarket should be beneficial in an inflationary environment, she said.
Mr Chew of Phillip Securities Research also said new stores ultimately drive revenue growth more than vouchers.
“Vouchers are likely substituting cash purchases of groceries, not increasing it,” he said.
Get our pick of top stories and thought-provoking articles in your inbox
Stay updated with notifications for breaking news and our best stories
Join our channel for the top reads for the day on your preferred chat app
昇菘超市在第三季度业绩报告中指出食品零售市场竞争激烈,受此影响,其股价在三个交易日内下跌了 15%。
顾客们提着购物袋离开昇菘超市。(图片:TODAY 资料图)
这段音频由人工智能工具生成。
新加坡:尽管昇菘超市的股价在三个交易日内下跌了 15%,但一些分析师仍然对这家超市运营商的前景持乐观态度。
“从结构上看,昇菘超市正在杂货领域,尤其是在生鲜食品销售方面,获得市场份额,”菲利普证券研究部研究主管周保罗先生周二(11月3日)告诉亚洲新闻台。
昇菘超市在截至9月30日的第三季度新开了三家分店,使该集团今年的新店数量达到七家。目前,该集团在新加坡共运营92家门店。
周先生认为,新店开业是公司增长和市场份额提升的核心驱动力,而过去两三年来,竞争有所减弱。
CGS国际证券也看好昇菘超市,分析师Meghana Kande表示,该公司盈利增长得益于新店扩张和强劲的运营执行。
CGS国际证券维持对昇菘银行的“增持”评级,而辉立证券则持“持有”评级。
RHB新加坡高级研究分析师Alfie Yeo对该股票给予“买入”评级。
杨先生表示:“我们相信,如果(昇菘集团)的盈利增长持续下去,其股价就会继续上涨。”
尽管前景黯淡,但形势依然良好。
昇菘超市股价在周五开始下跌,此前该公司公布了第三季度业绩,指出竞争激烈的食品零售市场和持续的促销活动给收入和利润率带来了压力。
管理层还强调了由于工资上涨和柴油价格上涨导致的成本上升,以及即将开通的新柔地铁系统(RTS)的影响,这可能会加剧价格竞争。
不过,该公司补充说,由于“在生活成本高企的情况下,消费者预计仍会注重性价比”,因此该公司有能力应对地缘政治的不确定性和干扰,以及来自 RTS Link 的潜在竞争。
净利润比上年同期增长1.8%。
该股周五收盘下跌 4.6%,周一又下跌 9.4%。
周二,该股再次下跌 2.5%,收于一年来的最低点。
华侨银行股票分析师朱鹏表示,此次抛售似乎是由对明年前景的悲观预期所致,而不是第三季度业绩所致。
她表示:“投资者已经将门店扩张速度放缓、电力和劳动力成本上升以及由此导致的利润率压力等风险考虑在内。”
CNA游戏 猜词游戏 逐行破解单词 流行词游戏 用给定的字母组成单词 迷你数独 小小谜题,挑战你的大脑 迷你填字游戏 小方格,大挑战 单词搜索 尽可能多地找出单词 显示更多 显示更少
朱女士补充说,该股目前的市盈率比历史平均水平高出两个标准差以上,“几乎没有令人失望的空间,而且在增长放缓和成本风险上升的情况下,该股更容易出现更大幅度的回调”。
CGS国际证券的坎德女士表示,该股今年以来涨势不错,投资者可能正在套现获利了结。
当被问及 SG60 代金券时,昇菘超市表示,该代金券在去年第三季度提振了收入和销售额,但 Kande 女士淡化了其影响,将代金券描述为“临时奖金”。
她表示,即使优惠券逐渐减少,昇菘超市作为物美价廉超市的根本定位在通货膨胀环境下仍将有利。
Phillip Securities Research 的 Chew 先生也表示,新店最终比代金券更能推动收入增长。
他说:“代金券很可能会取代现金购买食品杂货,而不是增加现金购买食品杂货。”
订阅我们的邮件,即可获取精选热点新闻和引人深思的文章。
订阅通知,第一时间获取突发新闻和精彩报道。
加入我们的频道,即可在您常用的聊天应用上获取当日热门文章。